Monthly SPY Straddle
By Big Data Federation, Inc.
Options are often priced as though future market moves will be larger than what ultimately occurs. Option sellers attempt to capture this volatility risk premium by collecting premiums that, on average, more than compensate for the realized movement of the underlying asset.
Here, we build a systematic options income strategy using the SPDR S&P 500 ETF (SPY). Rather than selling options continuously, we first apply a volatility filter using the CBOE Volatility Index (VIX), a widely used proxy for the market's expected volatility over the next 30 days. When the VIX is above 20, implied volatility is elevated, resulting in higher option premiums.
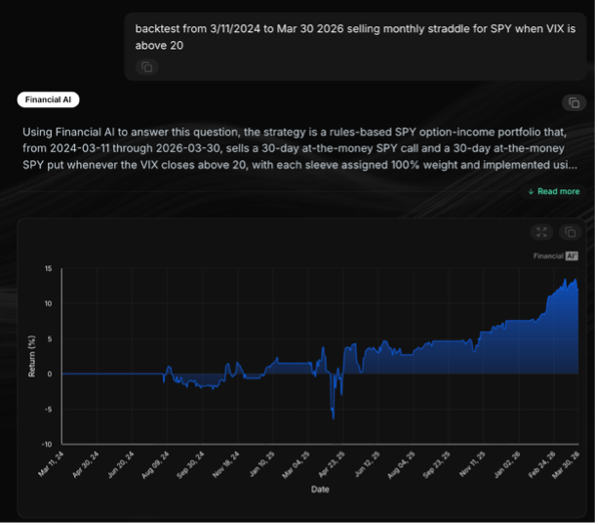
Our strategy is straightforward. From March 11, 2024 through March 30, 2026, each time the VIX closes above 20, we sell an at-the-money monthly SPY straddle by simultaneously selling one call option and one put option with the nearest monthly expiration. The position is then held until expiration before the strategy evaluates whether market conditions continue to meet the VIX threshold for initiating the next trade. The strategy’s performance is shown below:
 |
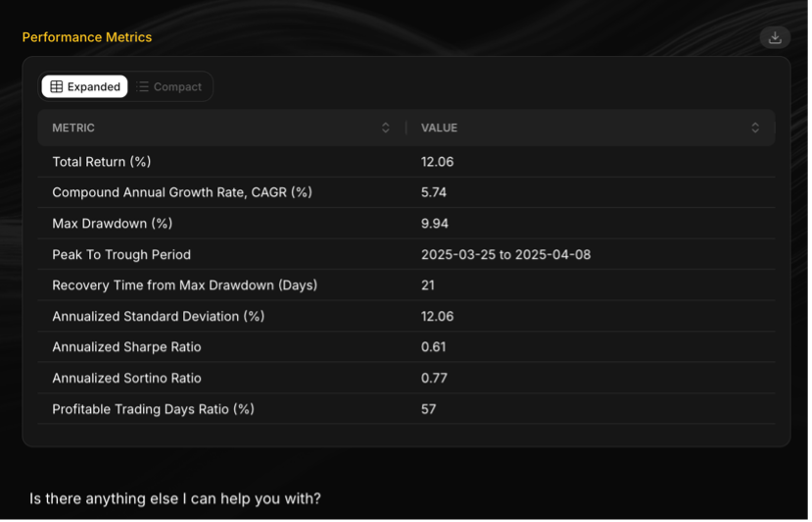 |
Over the test period, the strategy achieved a Sharpe ratio of 0.61 while limiting maximum drawdown to 9.9% and annualized volatility to 12.1%. Overall, 57% of trading days were profitable, demonstrating how a simple VIX filter can help create a disciplined, rules-based approach to harvesting option premium.
Published by Big Data Federation · All insights · Subscribe to Insights