Weekly SPY Iron Condor
By Big Data Federation, Inc.
Income-oriented options traders often use premium-selling strategies to generate consistent returns from the tendency of implied volatility to exceed realized volatility. One way to capture this volatility risk premium while defining risk on both sides of the market is through an iron condor.
Here, we build a systematic weekly iron condor strategy using the SPDR S&P 500 ETF (SPY). Rather than selling iron condors in every market environment, we apply a simple trend filter using SPY's 50-day moving average. When SPY trades above this level, the market is in an intermediate-term uptrend, which has historically been associated with more stable price action and fewer prolonged declines. In these conditions, the iron condor collects premium from both an out-of-the-money call spread and put spread, creating a range within which SPY can trade while the strategy remains profitable.
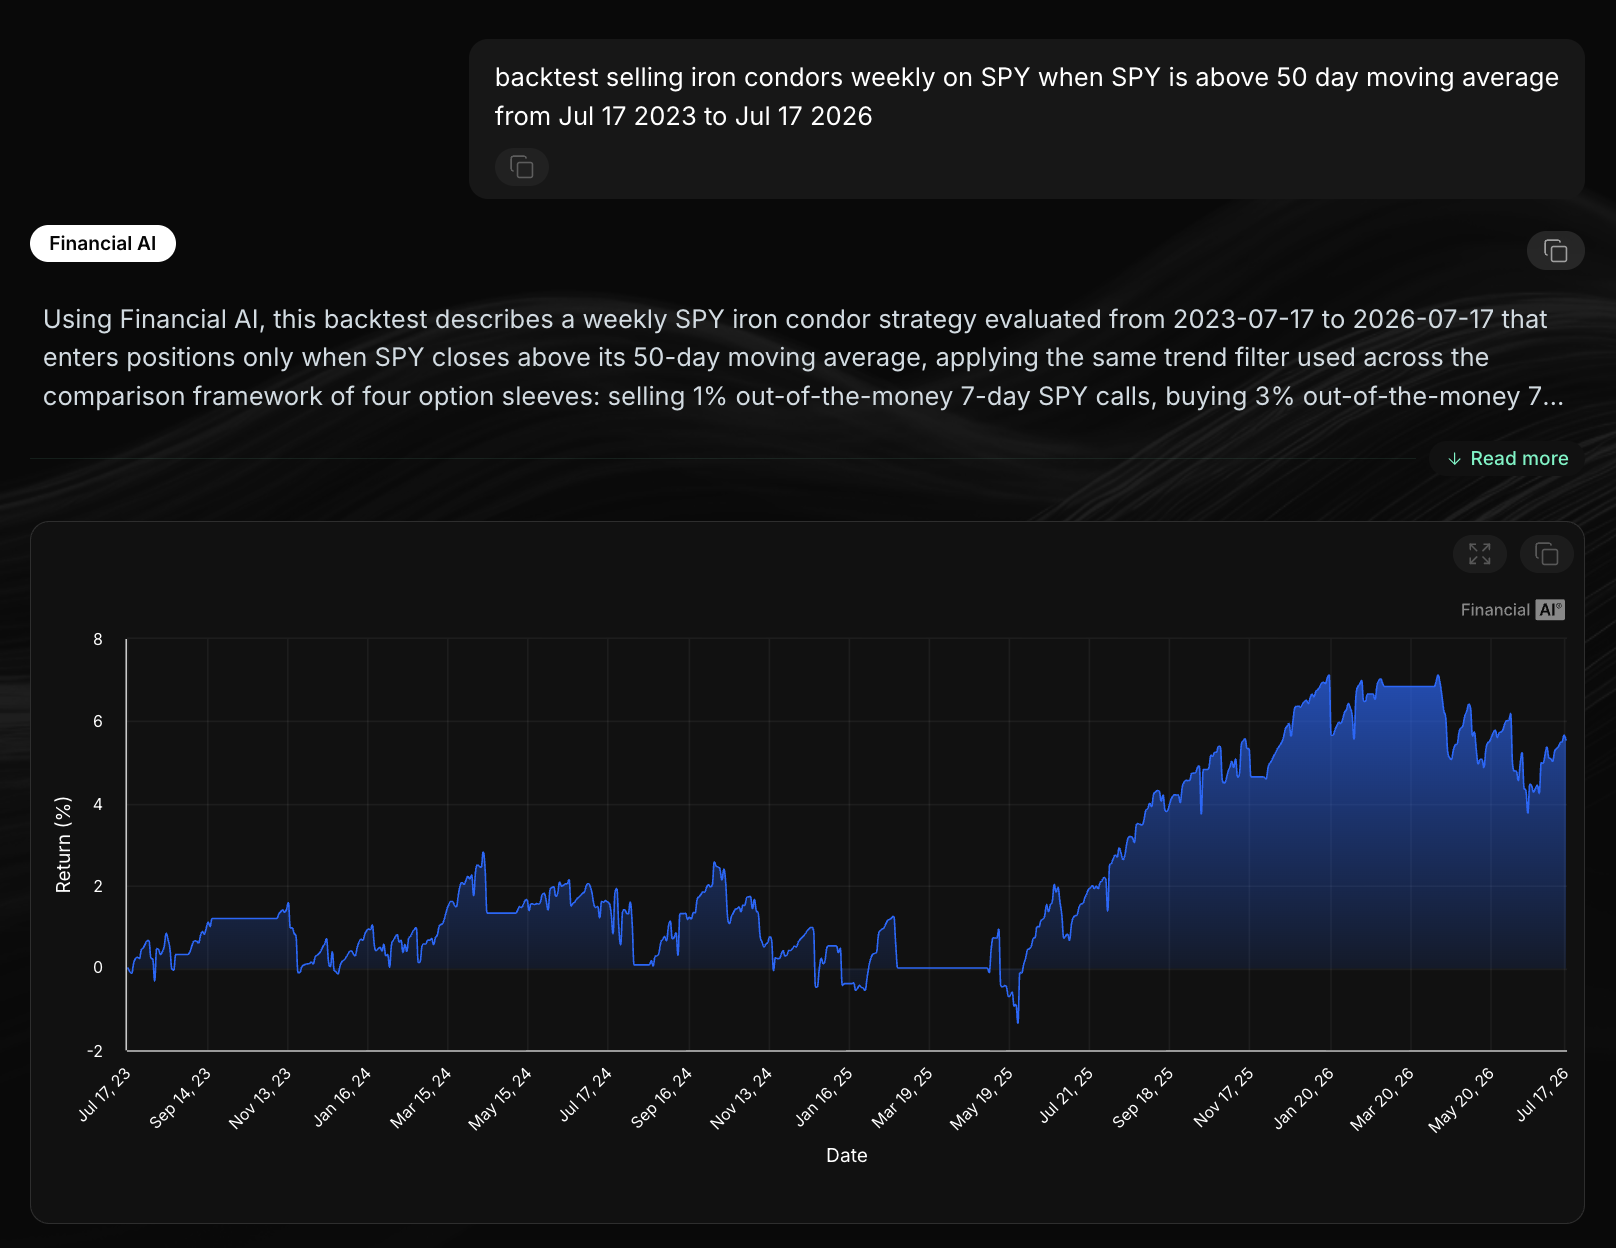
Our strategy is straightforward. From July 17, 2023, through July 17, 2026, each week that SPY is above its 50-day moving average, we sell a weekly SPY iron condor. Each position is held through the defined weekly holding period before the strategy evaluates whether SPY remains above its 50-day moving average and another iron condor should be initiated. The strategy’s performance is shown below.
 |
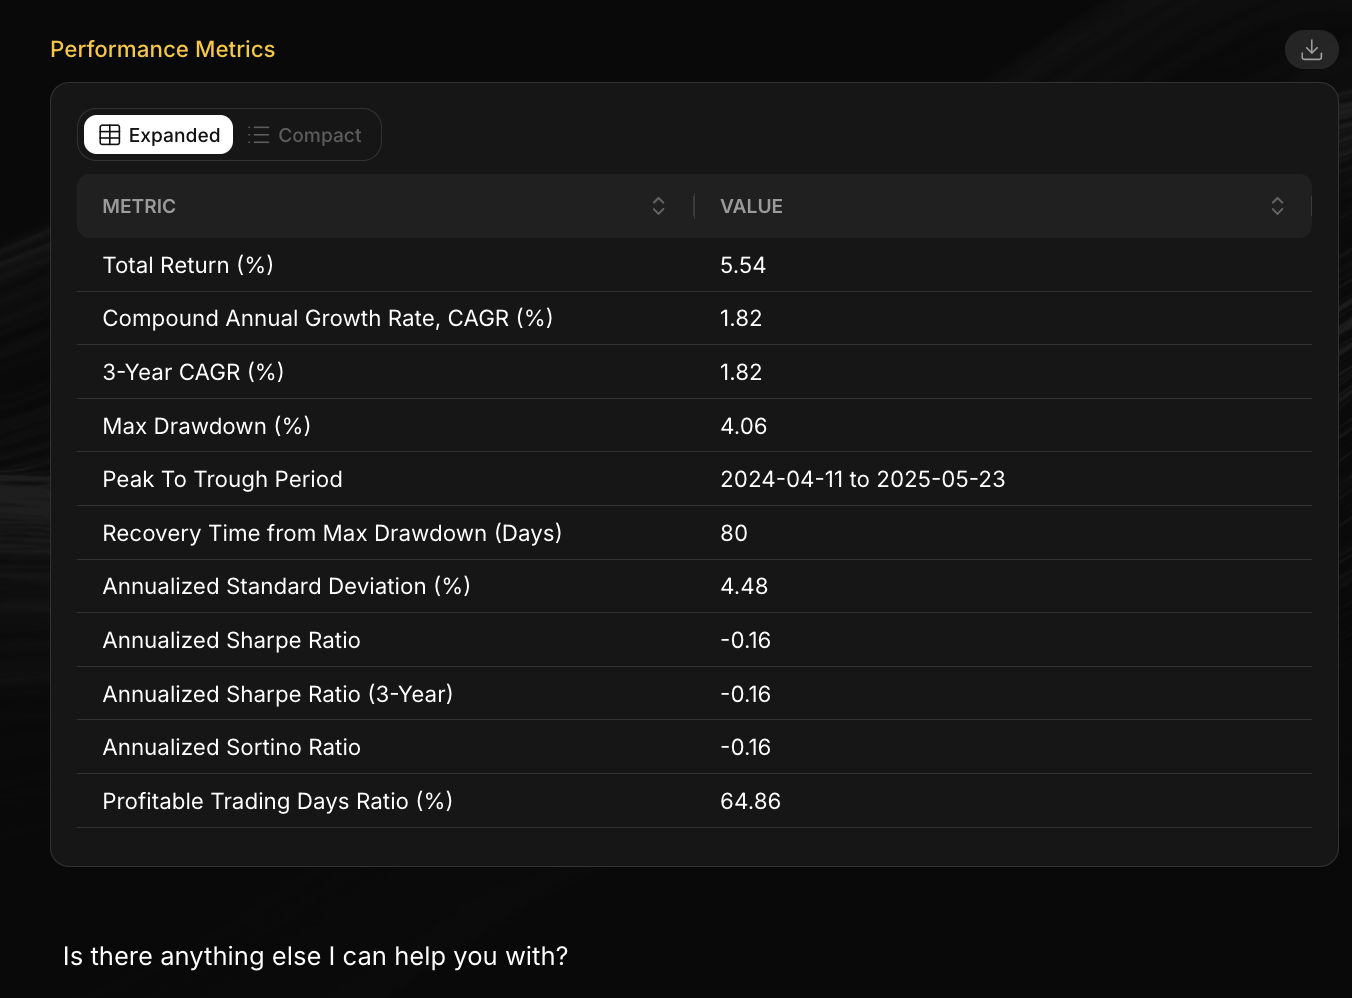 |
Over the test period, the strategy generated a total return of 5.5% while limiting maximum drawdown to 4.1% and annualized volatility to 4.5%. Overall, 64.9% of trading days were profitable, reflecting the high-probability nature of the iron condor structure.
Published by Big Data Federation · All insights · Subscribe to Insights