Uncertain Economic Environment Exerts Pressure on Hyperscalers’ Capital Spending
By Big Data Federation, Inc.
-
Economic headwinds negatively impacted 2H22 CapEx spending
-
Chinese hyperscalers, such as Baidu, Baba, and Tencent will experience a significant drop in CapEx
-
2023 data center CapEx will experience its slowest growth since 2019
Data centers’ victorious run is hitting some speed bumps. For CY2022, our algorithms forecast data center equipment (compute, network, and storage) spending to grow in the ten percent range year-over-year (YoY), a deacceleration compared to the high twenties seen in the past couple of years. For CY2023, our machines project mid-single-digit growth in hyperscale cloud providers’ equipment spending.
CY2022’s results stem from heavier workloads for AI/ML applications, which remain the key driver of computing demands. While YoY growth was approximately 20% during 1H22, it will cool to a mid-single-digit figure in 2H22 because of economic headwinds. 2H22 was heavily impacted by growing economic uncertainty as inflation did not decline persistently. Aggressive action by the Federal Reserve led to higher interest rates than initially expected, which tempered CapEx spending as companies face increased borrowing costs. Hyperscalers, highly rate sensitive, responded by easing CapEx after pursuing solid data center supply expansion in 2020 and 2021. We predict Chinese hyperscalers, such as Baidu, Baba, and Tencent, will have the most negative YoY CapEx growth, down nearly one-third; mainly driven by Tencent’s significantly lower CapEx investments caused by weaker financials in 2022.
CY2023 will face an even more marked slowdown. Our machines project mid-single-digit growth due to elevated rates and recession fears. A stubbornly tight job market raised concerns of triggering a wage-price spiral, and accordingly, the Federal Reserve upwardly revised their federal funds rate projections. In 1H23, we expect the Fed to continue raising rates, albeit at a slower pace. By 2H23, the effects of monetary tightening should work through the system, and it will be clear whether we arrive at a soft or hard landing. Regardless of if we enter a recession, data center CapEx growth will experience a stagnation after years of high growth.
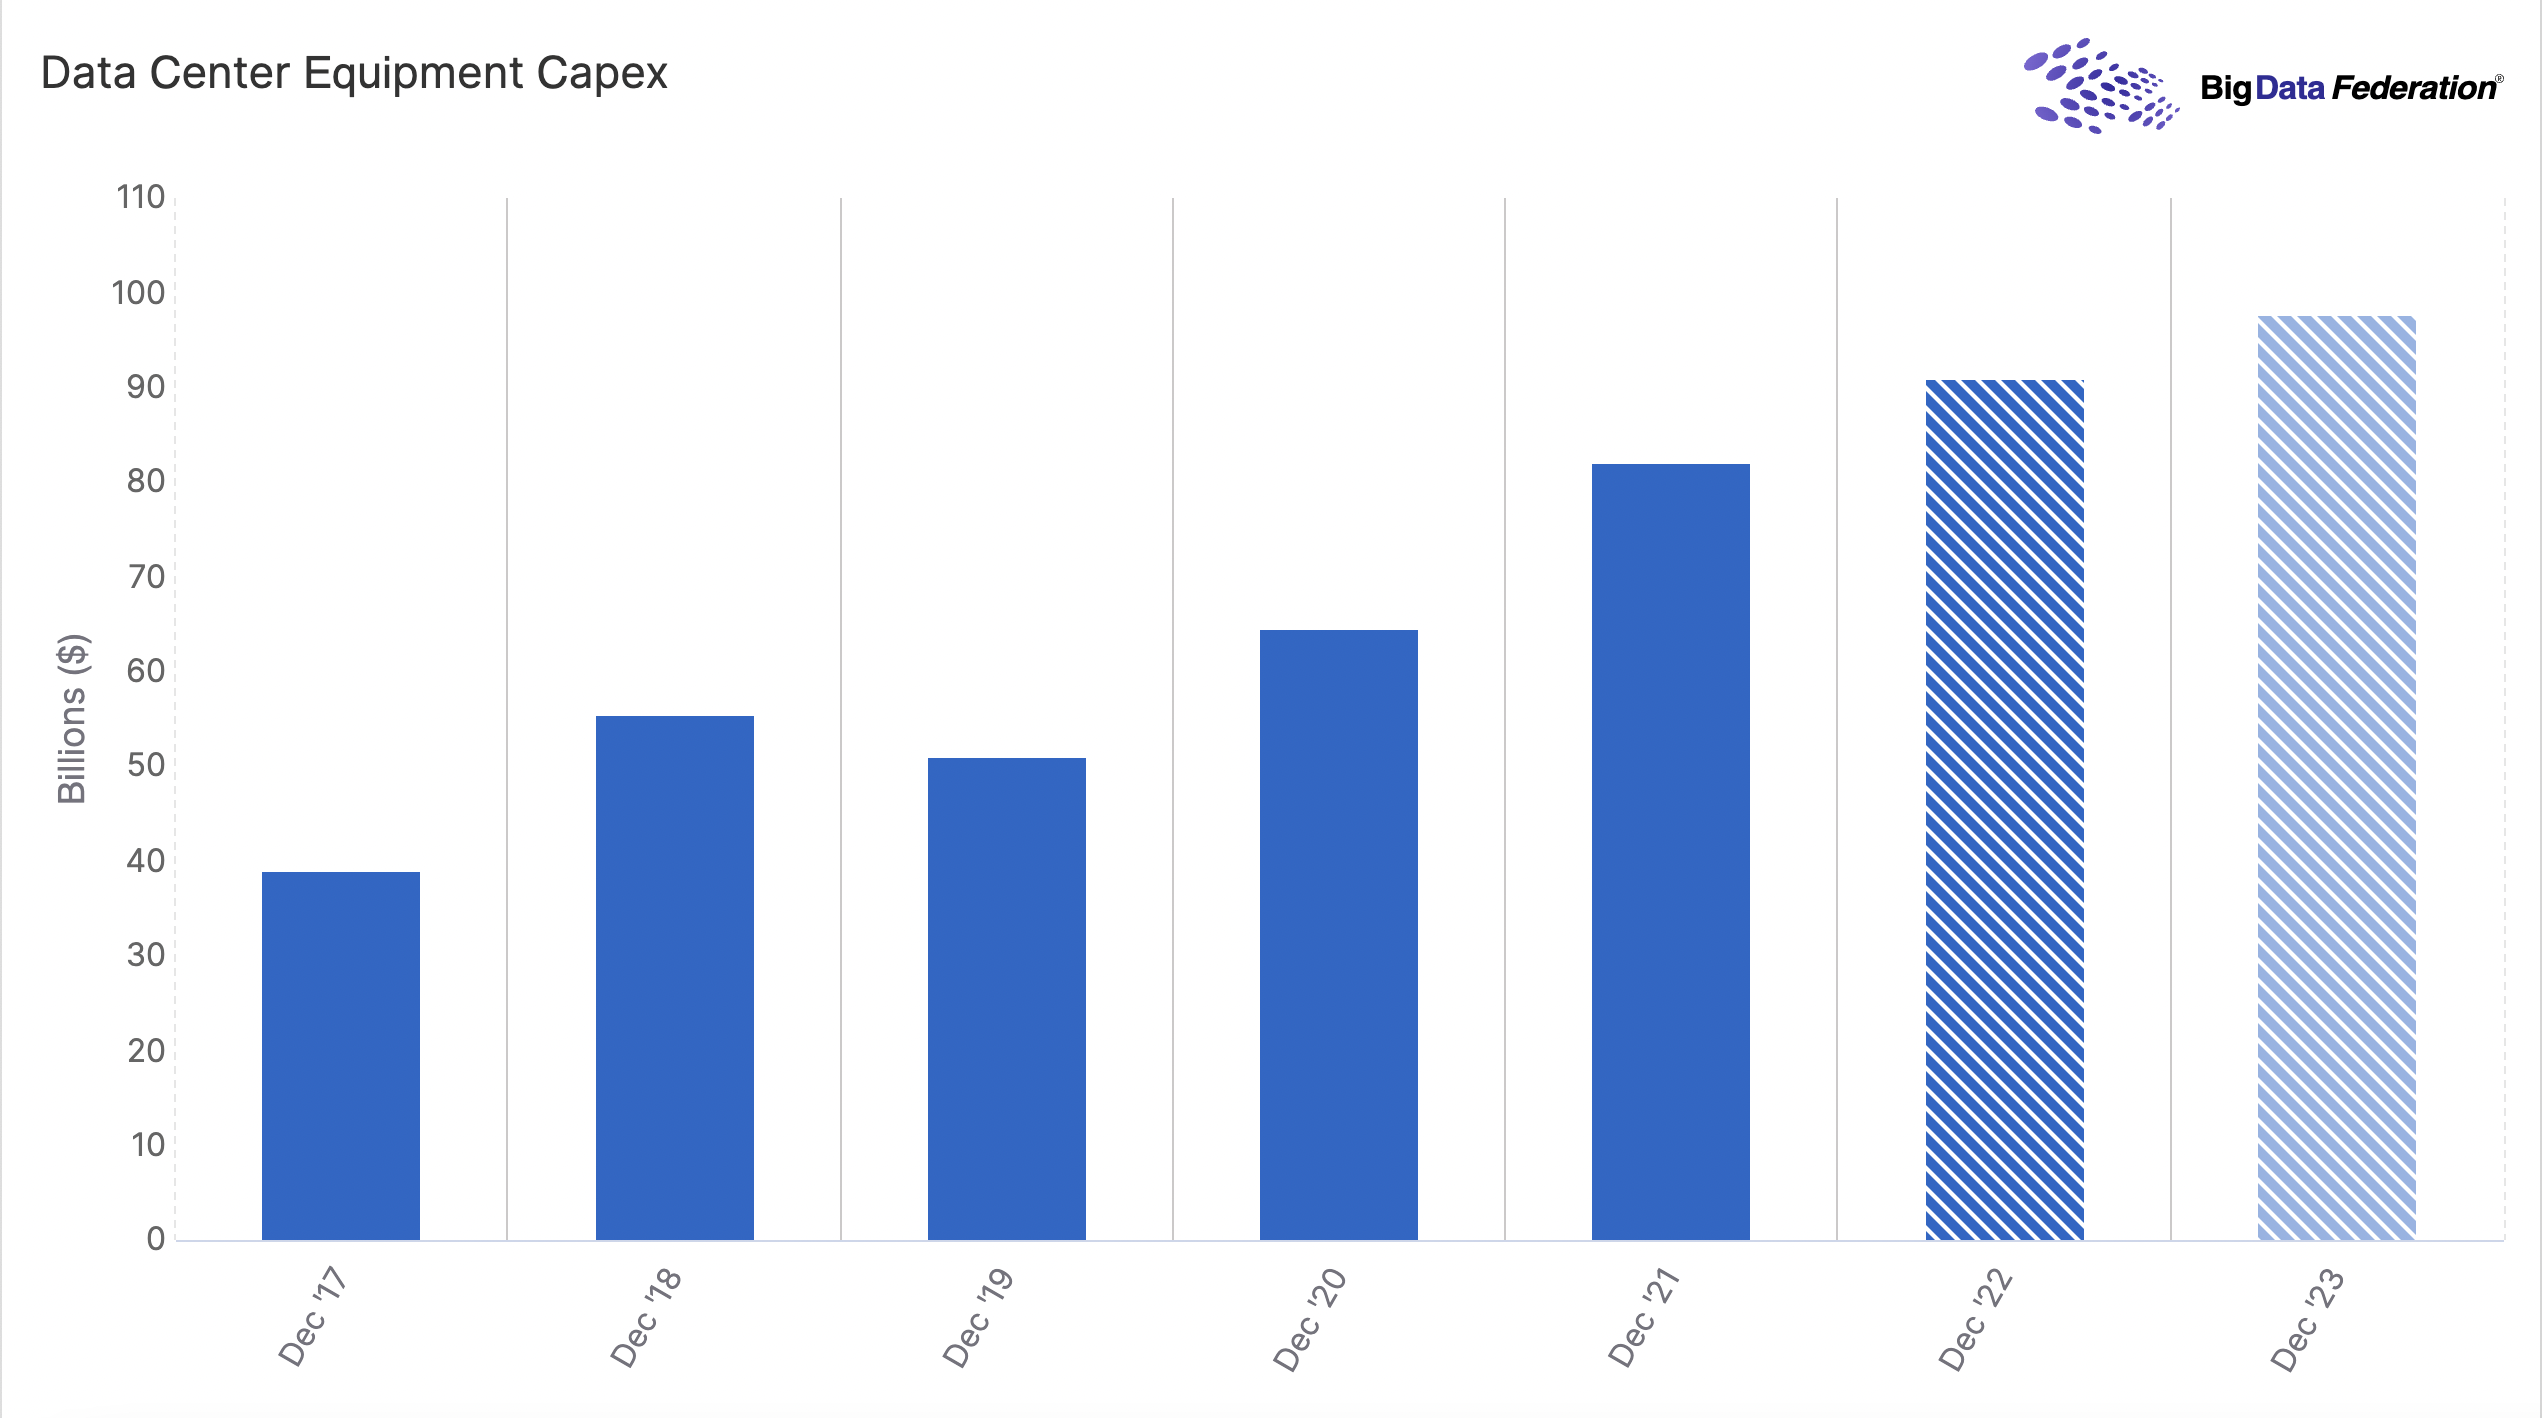
Nonetheless, the climbing demand for AI/ML, 5G, and edge computing will continue to benefit data center equipment spending. For example, Facebook’s heavy investment in their AI capacity for data centers in 2022 and likely in 2023. Two-thirds of CapEx spending will come from three major hyperscale cloud service providers (Amazon, Microsoft, and Alphabet), one-quarter will be from Facebook, Apple, and Chinese hyperscale cloud providers – while the rest will be from smaller players. Overall, economic factors remain at the forefront in 2023, which leads us to expect the lowest growth rates since 2019, where a brief absorption phase occurred after major growth in 2017 and 2018.
Published by Big Data Federation · All insights · Subscribe to Insights