S&P 500 Momentum Leaders
By Big Data Federation, Inc.
Momentum strategies are based on the idea that recent market leaders can continue to outperform over the near term. Rather than forecasting future winners, the strategy systematically follows stocks already showing strong relative performance.
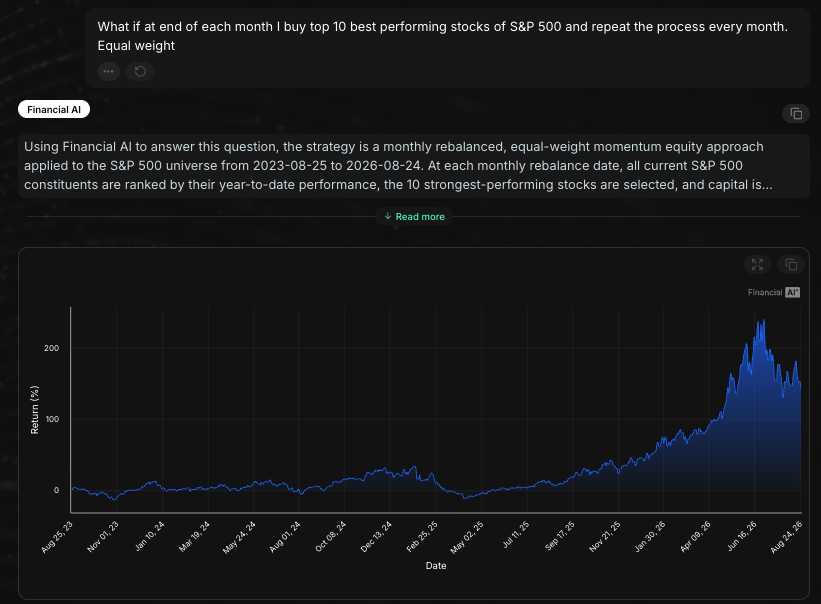
Here, we build a monthly momentum strategy using stocks in the S&P 500. At the end of each month, we rank all constituents by their return over the month that just ended and select the top 10. We invest equally across those names, giving each stock a 10% weigh, which prevents the largest companies from dominating.
The strategy is rebalanced at the end of every month. At each rebalance, we rank the S&P 500 again, replace the previous holdings with the latest top 10 performers, and hold them until the next month. This creates a systematic way to rotate into the market’s strongest-performing stocks.
 |
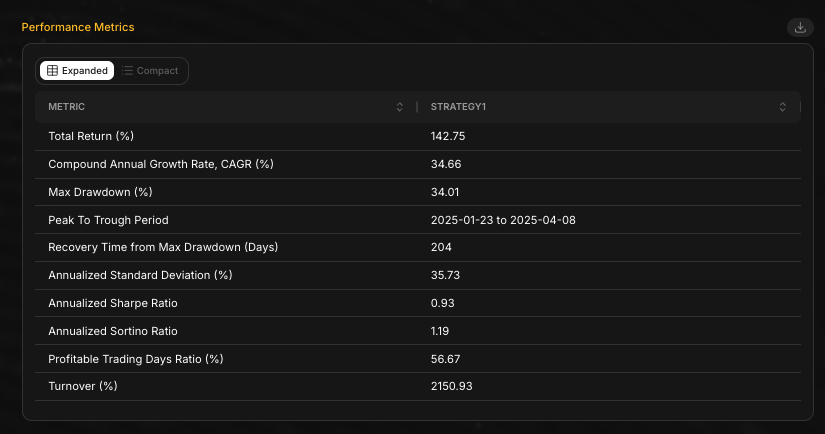 |
Overall, the strategy delivered strong backtested results, generating a 142.8% total return and 34.7% CAGR. Risk-adjusted performance was also solid, with a 0.93 Sharpe ratio and 1.19 Sortino ratio, while 56.7% of trading days were profitable.
Published by Big Data Federation · All insights · Subscribe to Insights