BTC with SPY Trend
By Big Data Federation, Inc.
Bitcoin investors often face a tradeoff between capturing the asset’s strong upside potential and managing the sharp drawdowns that can occur during periods of broader market weakness. Because Bitcoin often moves with broader investor risk appetite, the equity market can provide a useful source of cross-asset signals.
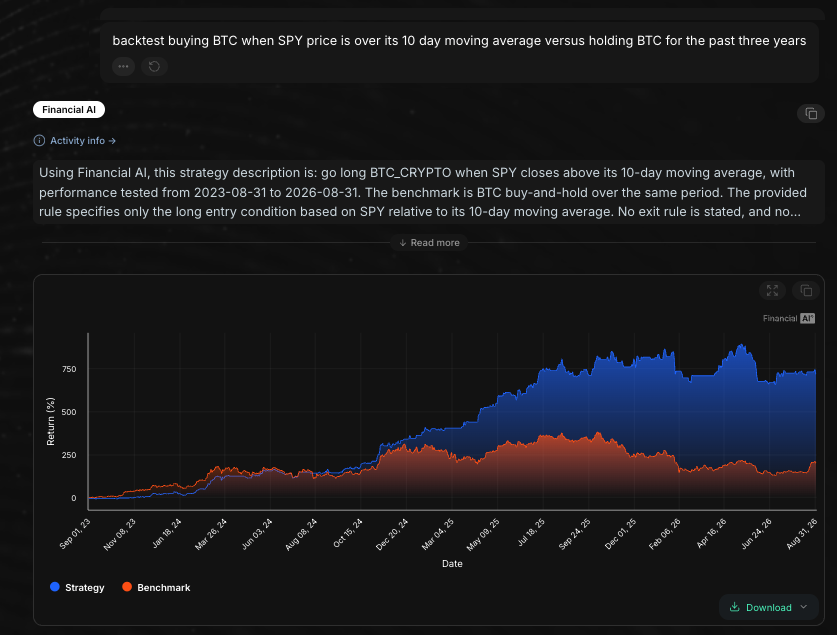
Here, we build a systematic Bitcoin (BTC) strategy using the SPDR S&P 500 ETF (SPY) as the signal. Rather than holding Bitcoin continuously, the strategy holds BTC only when SPY is trading above its 10-day moving average, which acts as a short-term indicator of broader market momentum and risk appetite. We compare the strategy with simply holding Bitcoin over the same three-year period.
 |
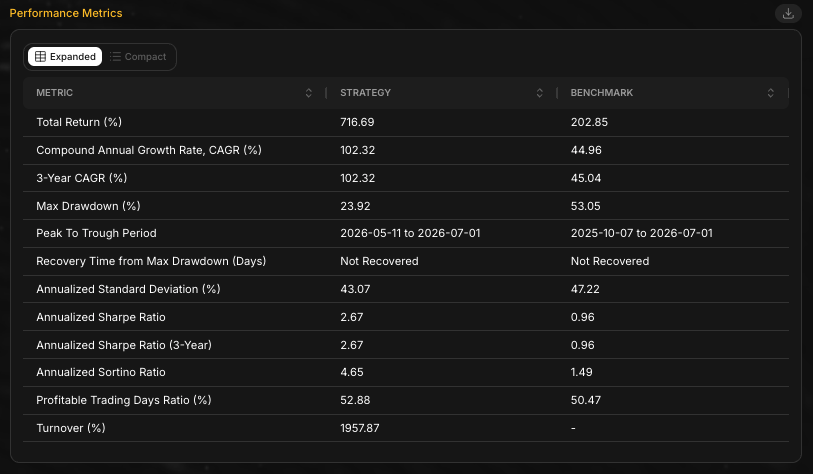 |
Overall, the cross-asset signal produced stronger results than simply holding Bitcoin for the past three years. The strategy generated a 716.7% total return versus 202.9%, while reducing maximum drawdown to 23.9% from 53.1%. Risk-adjusted performance also improved significantly, with a 2.67 Sharpe ratio and 4.65 Sortino ratio, compared with 0.96 and 1.49. Annualized volatility was slightly lower at 43.1%, while 52.9% of trading days were profitable.
Published by Big Data Federation · All insights · Subscribe to Insights