SPY 10-Minute Mean Reversion
By Big Data Federation, Inc.
Intraday traders often use short-term moving averages to identify temporary deviations in price and potential mean-reversion opportunities. When an asset trades below its recent average, it may indicate short-term weakness that could reverse as price moves back toward its prevailing trend. A systematic approach can be used to test whether repeatedly buying these brief pullbacks has historically generated attractive risk-adjusted returns.
Here, we build an intraday strategy using the SPDR S&P 500 ETF (SPY) and a 10-period moving average calculated on 1-minute bars. Rather than remaining continuously invested, the strategy takes a long position when SPY trades below its 10-minute moving average, seeking to capture short-term rebounds as price recovers toward its recent average. Because the strategy can generate frequent signals, we initially test it with 0 basis points of transaction costs to isolate the behavior of the underlying signal.
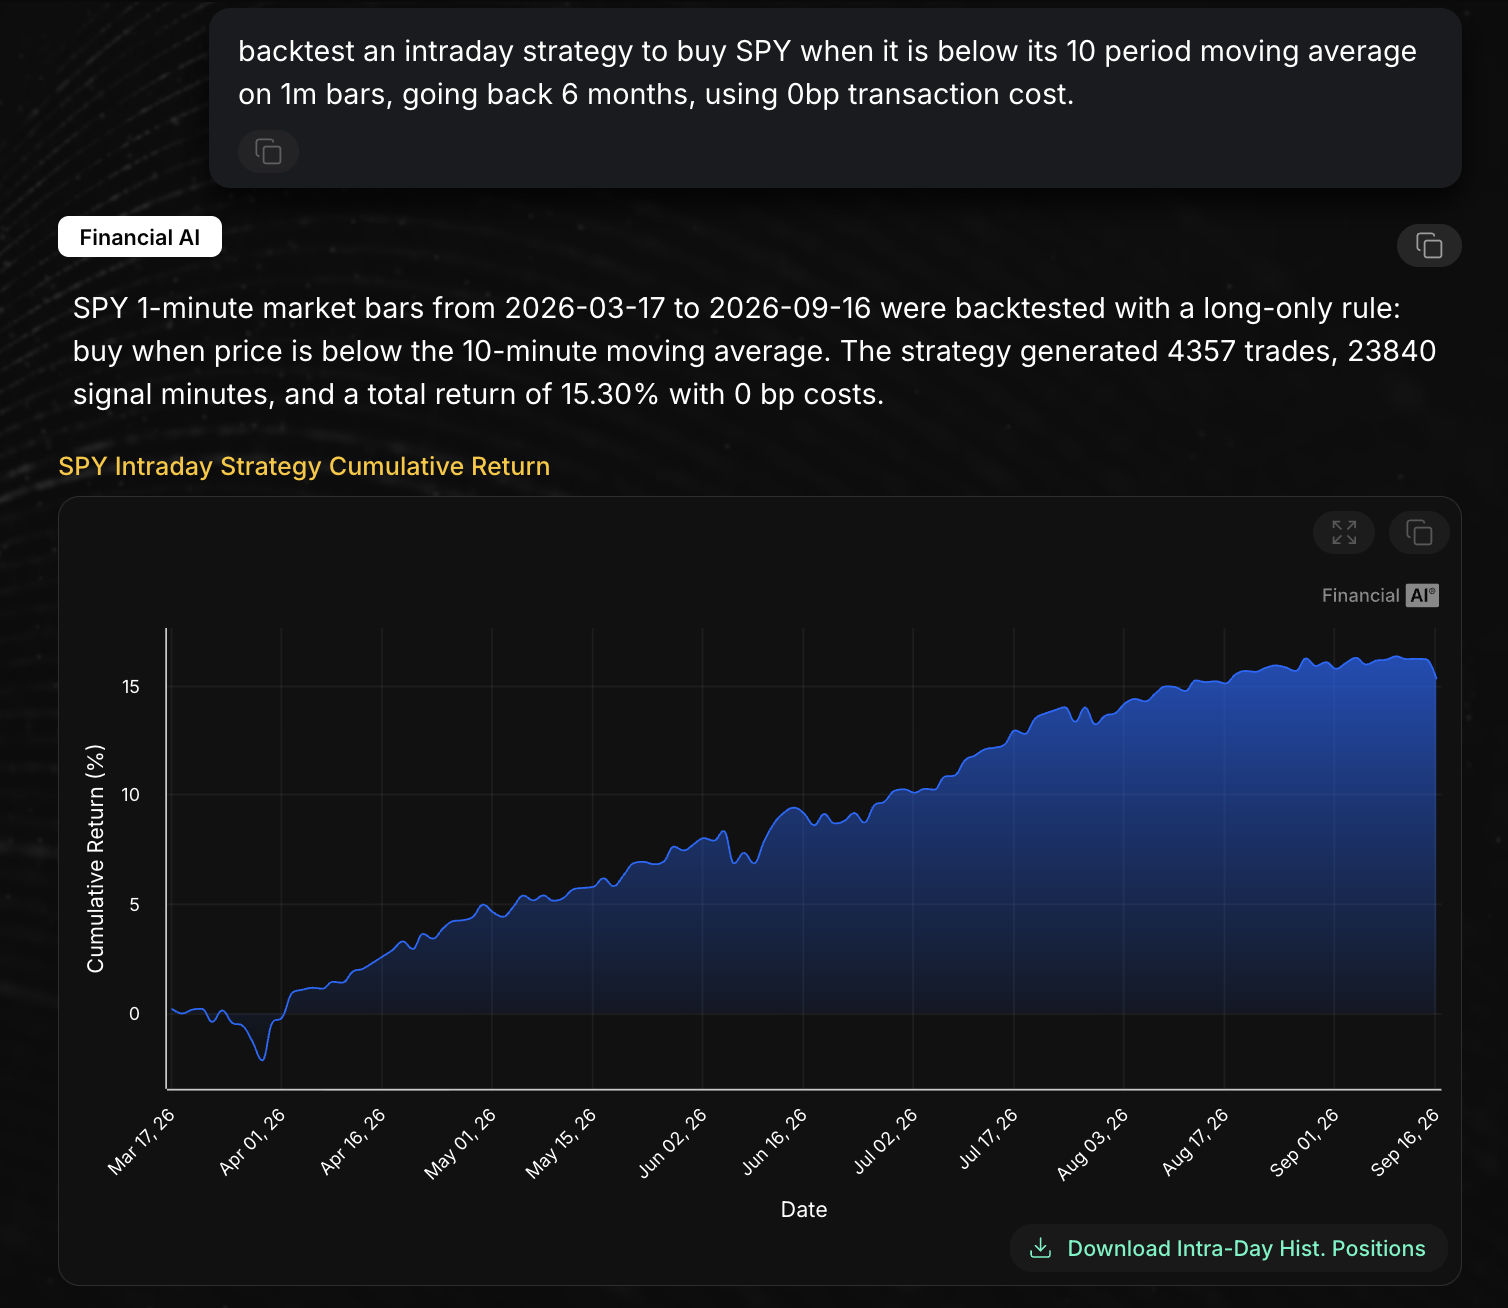
Our strategy is straightforward. From March 17, 2026, through September 16, 2026, we evaluate SPY every minute and buy when its price is below its 10-period moving average. The performance is shown below.
 |
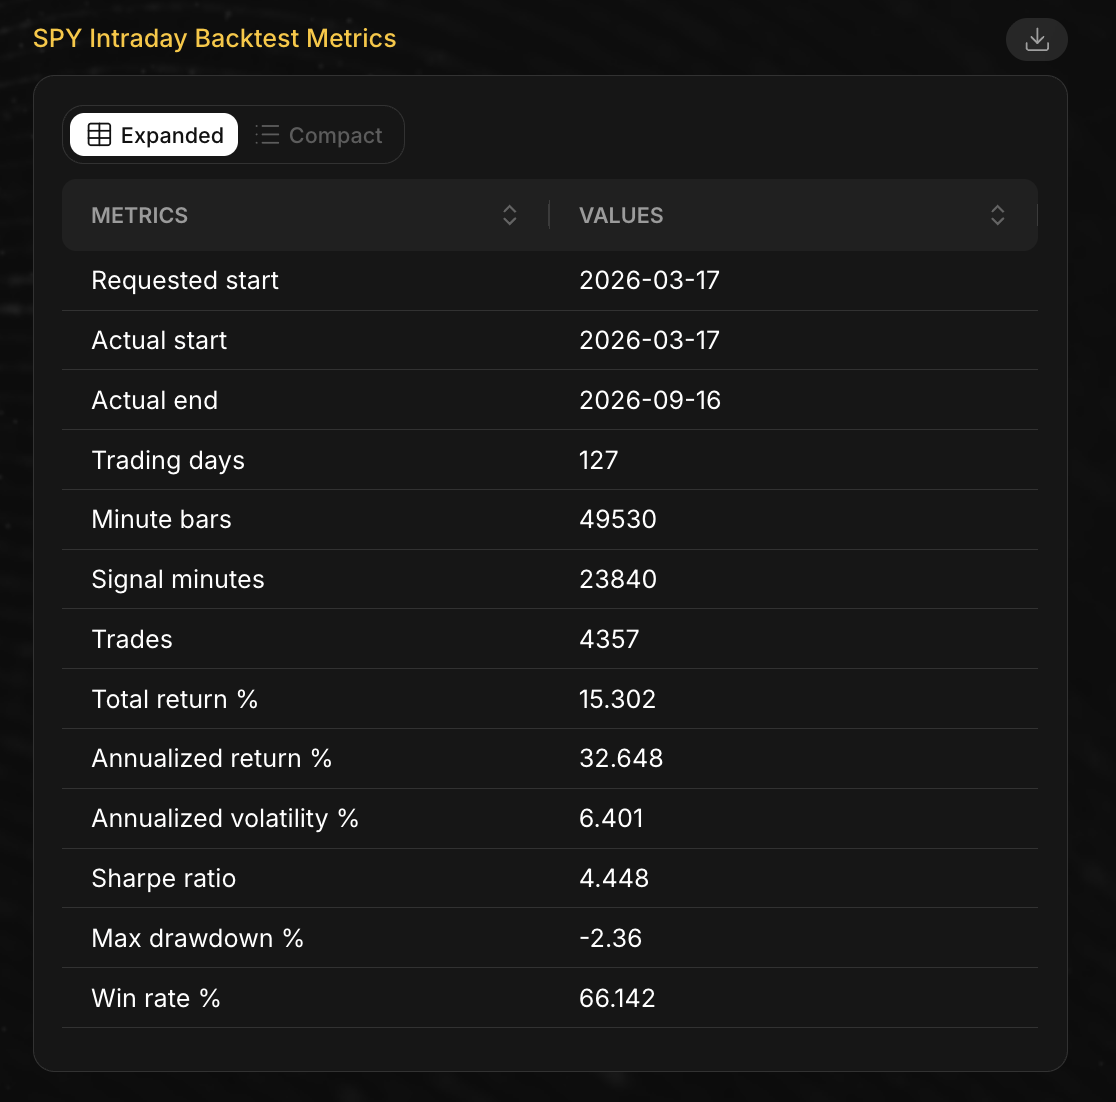 |
Over the six-month backtest, the strategy generated 4,357 trades across 127 trading days. It produced a 15.30% total return, with 6.40% annualized volatility, a 4.45 Sharpe ratio, and a maximum drawdown of 2.36%. The strategy recorded a 66.14% win rate, showing how a simple intraday mean-reversion rule performed over the tested period before accounting for transaction costs.
Published by Big Data Federation · All insights · Subscribe to Insights