Nikkei 225: Smoke and Mirrors?
By Big Data Federation, Inc.

The Japanese equity market has been delivering astonishing performance lately and after 26 years of stagnation, Nikkei 225 has finally broken through its 1989 peak. Nikkei 225’s outperformance seems very aggressive and above all 33 major global equity indexes this year. Our in-depth analysis indicates this apparent outperformance is incorrectly observed and unfounded. In a groundbreaking study leveraging cutting-edge technology trained for global financial analysis, we have conducted a thorough analysis of the Japanese equity market like never before. Here we go.
Price Action
As of April 25, 2024, the Nikkei 225 index has returned 13.0% while the S&P 500 index has returned 6.40%. The equity indices are formed by simple equations combining a select set of stock prices and possibly their corresponding share counts (in the case of cap-weighted indices such as the S&P 500) and then stabilized by divisors. The key point here is that the local currency has a significant influence on the value of any equity index. Now that we have stated the obvious, let’s see how Nikkei 225 performed excluding the currency impact. For a US investor, Nikkei 225 has only moved up 4.74% in US Dollars year to date. For a Japanese investor, the S&P 500 moved up 16.23% in Japanese Yen in the same period. In other words, the S&P 500 has outperformed the Nikkei 225 in whichever side of the ocean the investor lived. So yes, the price action is smoke and mirrors.
Fundamentals
Utilizing mass data aggregation of point-in-time information and natural language processing to understand geographic sales exposure, we have delved deep into the fundamentals of Nikkei 225 companies.
Our analysis focuses on several key financial metrics for companies listed in Nikkei 225, including sales, gross margin, EBITDA (earnings before interest, taxes, depreciation, and amortization), and EBITDA margin. Fundamental aggregations are based on real-time earnings dates, capturing the financial dynamics as they unfold, and focused only on companies with consistent reporting data. We conduct our evaluation in US Dollars to eliminate the effects of local currency fluctuations, employing a methodical approach that averages local currency over the fiscal quarter start and end dates for accurate US Dollar comparison.
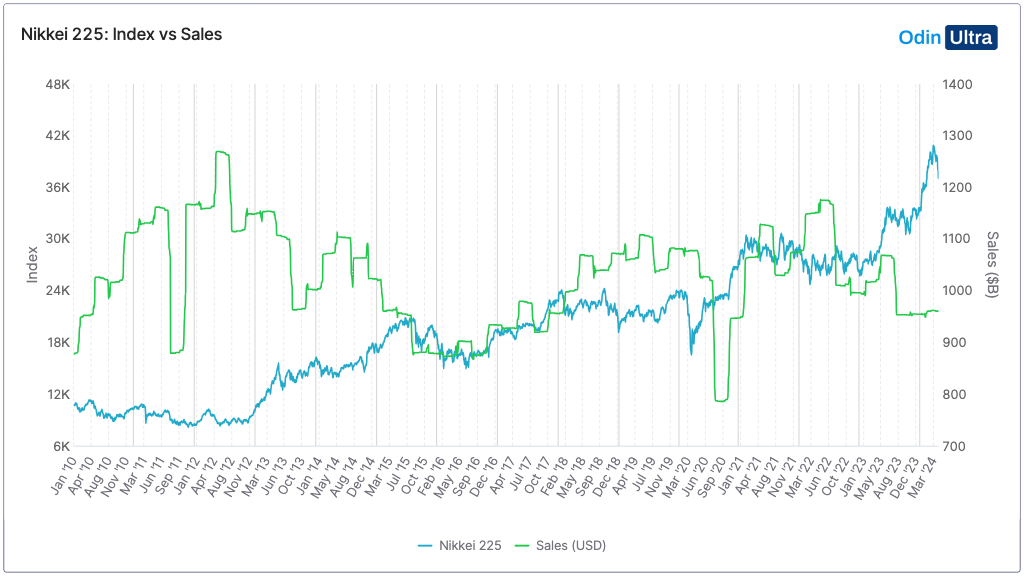
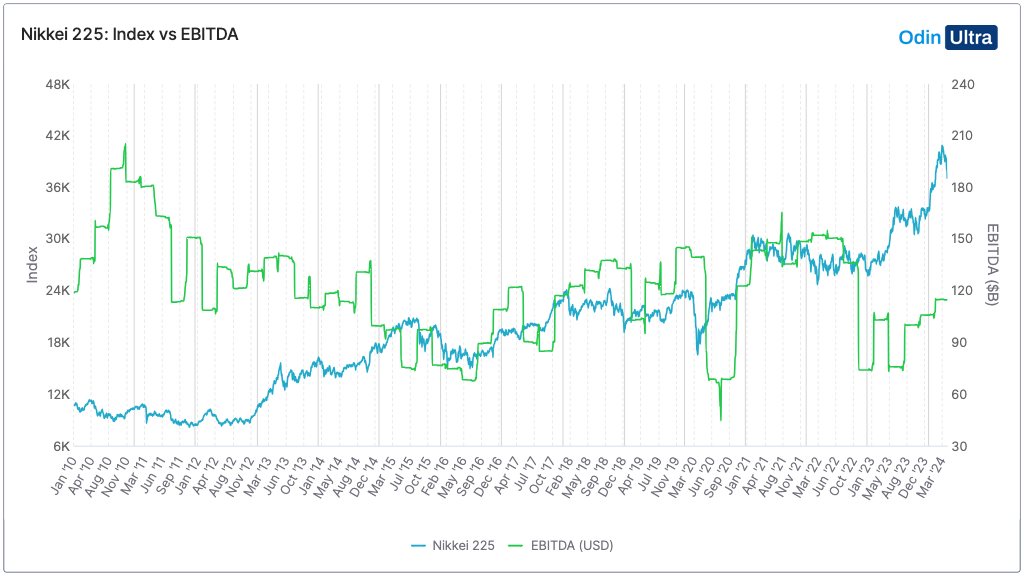
As shown below, the aggregated sales of Nikkei 225 companies in aggregation have demonstrated no growth, despite a consistent upward trend in prices. Even when using EBITDA — a measure intended to circumvent issues with bottom-line profitability and generally favors companies’ management — the trend stays the same. Notably, our approach does not account for survivorship bias, which should cast a more favorable light on Nikkei 225 fundamentals. However, despite this optimistic depiction, the underlying fundamental growth is markedly absent.
 |
 |
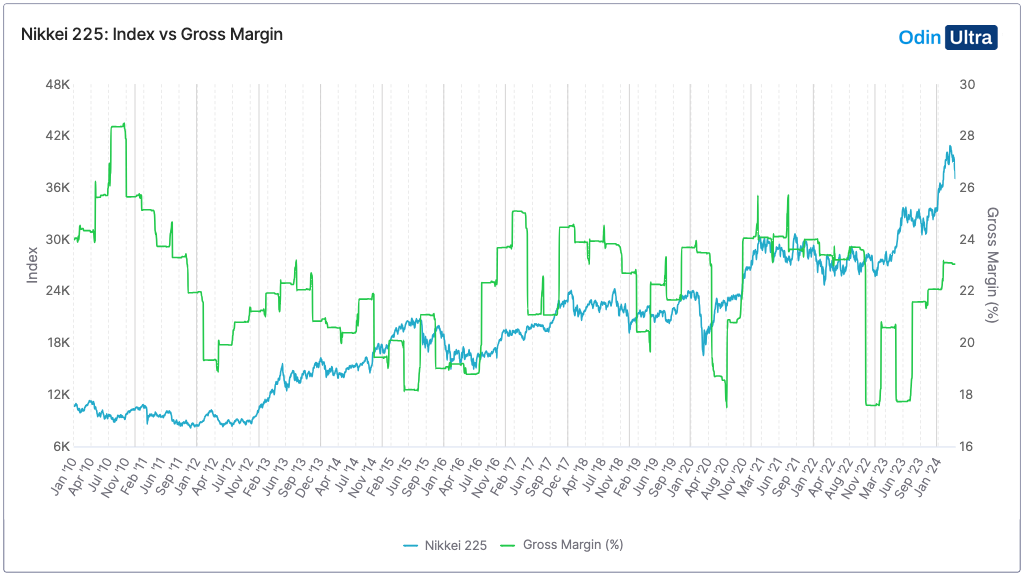
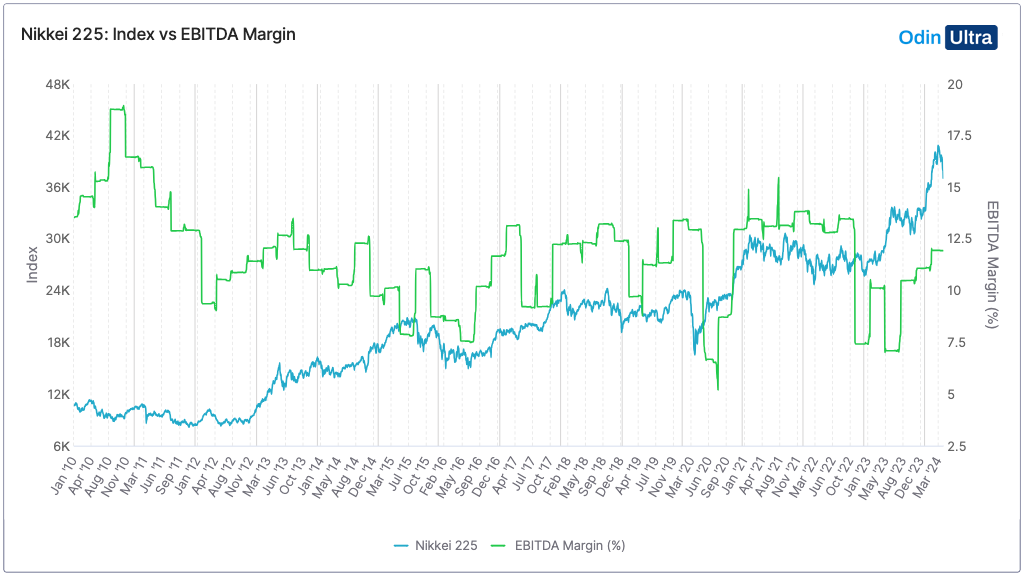
As illustrated below, the aggregate Nikkei 225 shows margins have also stagnated with no expansion whatsoever for the past 14 years. The Nikkei 225 aggregated gross and EBITDA margins are currently at 23% and 12%, respectively. S&P 500 is demonstrating much higher margins of 35% and 20% for gross income and EBITDA, respectively.
 |
 |
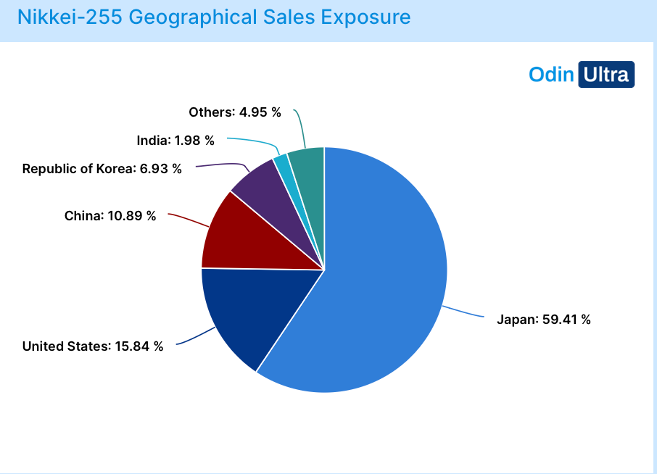
Our machines also automatically extracted geographical sales exposure for each company in the index from annual filings normalized proportionally to actual sales. Geographic sales distribution for Nikkei 225 companies, as demonstrated in the chart below, indicates that two-thirds of sales originations are from within Japan, mirroring the domestic sales focus observed in the S&P 500. In other words, the performance of Nikkei 225 companies is closely tied to their local economic conditions, much like those of the S&P 500.
Valuations
Valuation is complex and special care should be given to the methodology used. Mistakenly, market participants average valuation metrics of components of an index. Instead, we aggregate to avoid the skew of the averaging methods, which ignores the size of underlying fundamentals. The figure below illustrates our aggregated valuation for price to sales and price to EBITDA.
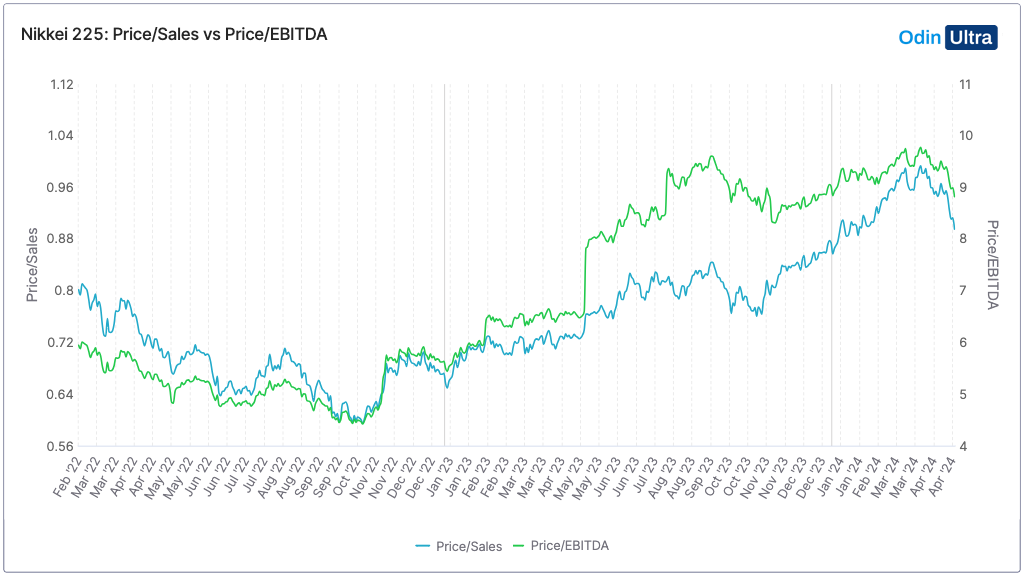
Since Nikkei 225's fundamentals have stagnated, the valuation of the index is completely determined by the price movement i.e. sentiment. Compared to the S&P 500, the Nikkei 225 valuation looks 50% cheaper due to the obvious lack of fundamentals growth.
Conclusion
In short, the statement that “Nikkei 225 has outperformed the S&P 500” is simply uneducated and not true. Nikkei 225 stocks remain cheap due to a good reason, no fundamentals growth. The higher valuation for Nikkei 225 should be backed by fundamental growth, otherwise, it will enter a risky proposition far more severe than the S&P 500 in the next global market meltdown.
Nikkei 225 companies used in this analysis
KYOWA KIRIN CO., LTD. (4151-JP), TAKEDA PHARMACEUTICAL CO., LTD. (4502-JP), ASTELLAS PHARMA INC. (4503-JP), SUMITOMO PHARMA CO., LTD. (4506-JP), SHIONOGI & CO., LTD. (4507-JP), CHUGAI PHARMACEUTICAL CO., LTD. (4519-JP), EISAI CO., LTD. (4523-JP), DAIICHI SANKYO CO., LTD. (4568-JP), OTSUKA HOLDINGS CO., LTD. (4578-JP), MINEBEA MITSUMI INC. (6479-JP), HITACHI, LTD. (6501-JP), MITSUBISHI ELECTRIC CORP. (6503-JP), FUJI ELECTRIC CO., LTD. (6504-JP), YASKAWA ELECTRIC CORP. (6506-JP), NIDEC CORP. (6594-JP), OMRON CORP. (6645-JP), GS YUASA CORP. (6674-JP), NEC CORP. (6701-JP), FUJITSU LTD. (6702-JP), RENESAS ELECTRONICS CORP. (6723-JP), SEIKO EPSON CORP. (6724-JP), PANASONIC HOLDINGS CORP. (6752-JP), SHARP CORP. (6753-JP), SONY GROUP CORP. (6758-JP), TDK CORP. (6762-JP), ALPS ALPINE CO., LTD. (6770-JP), YOKOGAWA ELECTRIC CORP. (6841-JP), ADVANTEST CORP. (6857-JP), KEYENCE CORP. (6861-JP), DENSO CORP. (6902-JP), LASERTEC CORP. (6920-JP), CASIO COMPUTER CO., LTD. (6952-JP), FANUC CORP. (6954-JP), KYOCERA CORP. (6971-JP), TAIYO YUDEN CO., LTD. (6976-JP), MURATA MANUFACTURING CO., LTD. (6981-JP), SCREEN HOLDINGS CO., LTD. (7735-JP), CANON INC. (7751-JP), RICOH CO., LTD. (7752-JP), TOKYO ELECTRON LTD. (8035-JP), NISSAN MOTOR CO., LTD. (7201-JP), ISUZU MOTORS LTD. (7202-JP), TOYOTA MOTOR CORP. (7203-JP), HINO MOTORS, LTD. (7205-JP), MITSUBISHI MOTORS CORP. (7211-JP), MAZDA MOTOR CORP. (7261-JP), HONDA MOTOR CO., LTD. (7267-JP), SUZUKI MOTOR CORP. (7269-JP), SUBARU CORP. (7270-JP), YAMAHA MOTOR CO., LTD. (7272-JP), TERUMO CORP. (4543-JP), KONICA MINOLTA, INC. (4902-JP), NIKON CORP. (7731-JP), OLYMPUS CORP. (7733-JP), HOYA CORP. (7741-JP), CITIZEN WATCH CO., LTD. (7762-JP), NIPPON TELEGRAPH & TELEPHONE CORP. (9432-JP), KDDI CORP. (9433-JP), SOFTBANK CORP. (9434-JP), NTT DATA GROUP CORP. (9613-JP), SOFTBANK GROUP CORP. (9984-JP), SHIZUOKA FINANCIAL GROUP, INC. (5831-JP), CONCORDIA FINANCIAL GROUP, LTD. (7186-JP), AOZORA BANK, LTD. (8304-JP), MITSUBISHI UFJ FINANCIAL GROUP, INC. (8306-JP), RESONA HOLDINGS, INC. (8308-JP), SUMITOMO MITSUI TRUST HOLDINGS, INC. (8309-JP), SUMITOMO MITSUI FINANCIAL GROUP, INC. (8316-JP), THE CHIBA BANK, LTD. (8331-JP), FUKUOKA FINANCIAL GROUP, INC. (8354-JP), MIZUHO FINANCIAL GROUP, INC. (8411-JP), CREDIT SAISON CO., LTD. (8253-JP), ORIX CORP. (8591-JP), JAPAN EXCHANGE GROUP, INC. (8697-JP), DAIWA SECURITIES GROUP INC. (8601-JP), NOMURA HOLDINGS, INC. (8604-JP), SOMPO HOLDINGS, INC. (8630-JP), MS&AD INSURANCE GROUP HOLDINGS, INC. (8725-JP), DAI-ICHI LIFE HOLDINGS, INC. (8750-JP), TOKIO MARINE HOLDINGS, INC. (8766-JP), T&D HOLDINGS, INC. (8795-JP), NISSUI CORP. (1332-JP), NISSHIN SEIFUN GROUP INC. (2002-JP), MEIJI HOLDINGS CO., LTD. (2269-JP), NH FOODS LTD. (2282-JP), SAPPORO HOLDINGS LTD. (2501-JP), ASAHI GROUP HOLDINGS, LTD. (2502-JP), KIRIN HOLDINGS CO., LTD. (2503-JP), TAKARA HOLDINGS INC. (2531-JP), KIKKOMAN CORP. (2801-JP), AJINOMOTO CO., INC. (2802-JP), NICHIREI CORP. (2871-JP), JAPAN TOBACCO INC. (2914-JP), J.FRONT RETAILING CO., LTD. (3086-JP), ISETAN MITSUKOSHI HOLDINGS LTD. (3099-JP), SEVEN & I HOLDINGS CO., LTD. (3382-JP), TAKASHIMAYA CO., LTD. (8233-JP), MARUI GROUP CO., LTD. (8252-JP), AEON CO., LTD. (8267-JP), NITORI HOLDINGS CO., LTD. (9843-JP), FAST RETAILING CO., LTD. (9983-JP), M3, INC. (2413-JP), DENA CO., LTD. (2432-JP), NEXON CO., LTD. (3659-JP), DENTSU GROUP INC. (4324-JP), MERCARI, INC. (4385-JP), ORIENTAL LAND CO., LTD. (4661-JP), LY CORP. (4689-JP), TREND MICRO INC. (4704-JP), CYBERAGENT, INC. (4751-JP), RAKUTEN GROUP, INC. (4755-JP), RECRUIT HOLDINGS CO., LTD. (6098-JP), JAPAN POST HOLDINGS CO., LTD. (6178-JP), NINTENDO CO., LTD. (7974-JP), TOHO CO., LTD (9602-JP), SECOM CO., LTD. (9735-JP), KONAMI GROUP CORP. (9766-JP), INPEX CORP. (1605-JP), TEIJIN LTD. (3401-JP), TORAY INDUSTRIES, INC. (3402-JP), OJI HOLDINGS CORP. (3861-JP), NIPPON PAPER INDUSTRIES CO., LTD. (3863-JP), KURARAY CO., LTD. (3405-JP), ASAHI KASEI CORP. (3407-JP), RESONAC HOLDINGS CORP. (4004-JP), SUMITOMO CHEMICAL CO., LTD. (4005-JP), NISSAN CHEMICAL CORP. (4021-JP), TOSOH CORP. (4042-JP), TOKUYAMA CORP. (4043-JP), DENKA CO., LTD. (4061-JP), SHIN-ETSU CHEMICAL CO., LTD. (4063-JP), MITSUI CHEMICALS, INC. (4183-JP), MITSUBISHI CHEMICAL GROUP CORP. (4188-JP), UBE CORP. (4208-JP), KAO CORP. (4452-JP), DIC CORP. (4631-JP), FUJIFILM HOLDINGS CORP. (4901-JP), SHISEIDO CO., LTD. (4911-JP), NITTO DENKO CORP. (6988-JP), IDEMITSU KOSAN CO., LTD. (5019-JP), ENEOS HOLDINGS, INC. (5020-JP), THE YOKOHAMA RUBBER CO., LTD. (5101-JP), BRIDGESTONE CORP. (5108-JP), AGC INC. (5201-JP), NIPPON ELECTRIC GLASS CO., LTD. (5214-JP), SUMITOMO OSAKA CEMENT CO., LTD. (5232-JP), TAIHEIYO CEMENT CORP. (5233-JP), TOKAI CARBON CO., LTD. (5301-JP), TOTO LTD. (5332-JP), NGK INSULATORS, LTD. (5333-JP), NIPPON STEEL CORP. (5401-JP), KOBE STEEL, LTD. (5406-JP), JFE HOLDINGS, INC. (5411-JP), PACIFIC METALS CO., LTD. (5541-JP), SUMCO CORP. (3436-JP), MITSUI MINING & SMELTING CO. (5706-JP), MITSUBISHI MATERIALS CORP. (5711-JP), SUMITOMO METAL MINING CO., LTD. (5713-JP), DOWA HOLDINGS CO., LTD. (5714-JP), FURUKAWA ELECTRIC CO., LTD. (5801-JP), SUMITOMO ELECTRIC IND., LTD. (5802-JP), FUJIKURA LTD. (5803-JP), SOJITZ CORP. (2768-JP), ITOCHU CORP. (8001-JP), MARUBENI CORP. (8002-JP), TOYOTA TSUSHO CORP. (8015-JP), MITSUI & CO., LTD. (8031-JP), SUMITOMO CORP. (8053-JP), MITSUBISHI CORP. (8058-JP), COMSYS HOLDINGS CORP. (1721-JP), TAISEI CORP. (1801-JP), OBAYASHI CORP. (1802-JP), SHIMIZU CORP. (1803-JP), HASEKO CORP. (1808-JP), KAJIMA CORP. (1812-JP), DAIWA HOUSE IND. CO., LTD. (1925-JP), SEKISUI HOUSE, LTD. (1928-JP), JGC HOLDINGS CORP. (1963-JP), THE JAPAN STEEL WORKS, LTD. (5631-JP), OKUMA CORP. (6103-JP), AMADA CO., LTD. (6113-JP), SMC CORP. (6273-JP), KOMATSU LTD. (6301-JP), SUMITOMO HEAVY IND., LTD. (6302-JP), HITACHI CONST. MACH. CO., LTD. (6305-JP), KUBOTA CORP. (6326-JP), EBARA CORP. (6361-JP), DAIKIN INDUSTRIES, LTD. (6367-JP), NSK LTD. (6471-JP), NTN CORP. (6472-JP), JTEKT CORP. (6473-JP), HITACHI ZOSEN CORP. (7004-JP), MITSUBISHI HEAVY IND., LTD. (7011-JP), IHI CORP. (7013-JP), KAWASAKI HEAVY IND., LTD. (7012-JP), BANDAI NAMCO HOLDINGS INC. (7832-JP), TOPPAN HOLDINGS INC. (7911-JP), DAI NIPPON PRINTING CO., LTD. (7912-JP), YAMAHA CORP. (7951-JP), TOKYU FUDOSAN HOLDINGS CORP. (3289-JP), MITSUI FUDOSAN CO., LTD. (8801-JP), MITSUBISHI ESTATE CO., LTD. (8802-JP), TOKYO TATEMONO CO., LTD. (8804-JP), SUMITOMO REALTY & DEVELOPMENT CO., LTD. (8830-JP), TOBU RAILWAY CO., LTD. (9001-JP), TOKYU CORP. (9005-JP), ODAKYU ELECTRIC RAILWAY CO., LTD. (9007-JP), KEIO CORP. (9008-JP), KEISEI ELECTRIC RAILWAY CO., LTD. (9009-JP), EAST JAPAN RAILWAY CO. (9020-JP), WEST JAPAN RAILWAY CO. (9021-JP), CENTRAL JAPAN RAILWAY CO., LTD. (9022-JP), YAMATO HOLDINGS CO., LTD. (9064-JP), NIPPON EXPRESS HOLDINGS, INC. (9147-JP), NIPPON YUSEN K.K. (9101-JP), MITSUI O.S.K.LINES, LTD. (9104-JP), KAWASAKI KISEN KAISHA, LTD. (9107-JP), JAPAN AIRLINES CO., LTD. (9201-JP), ANA HOLDINGS INC. (9202-JP), MITSUBISHI LOGISTICS CORP. (9301-JP), TOKYO ELECTRIC POWER COMPANY HOLDINGS, I (9501-JP), CHUBU ELECTRIC POWER CO., INC. (9502-JP), THE KANSAI ELECTRIC POWER CO., INC. (9503-JP), TOKYO GAS CO., LTD. (9531-JP), OSAKA GAS CO., LTD. (9532-JP)
About OdinUltra
OdinUltra is a cutting-edge no-code specialized AI platform, designed to cater to a wide array of professionals in the asset management industry. It is a battle-tested specialized partner that empowers users including discretionary, quantitative, multi-asset, and multi-strategy managers to harness the immense potential of big data and sophisticated investment techniques. From idea exploration and construction to verification and deployment, OdinUltra is an all-encompassing tool. Asset managers can enhance existing products and rapidly develop new ones, securing a competitive edge in the dynamic world of asset management.
Published by Big Data Federation · All insights · Subscribe to Insights