Generative AI Driving Cloud Hyperscalers' Spending
By Big Data Federation, Inc.

-
Uncertain economic environment curbed hyperscalers’ CapEx spending in 1H23
-
Ongoing shifts in capital expenditure from conventional servers to AI servers
-
CapEx to substantially accelerate in 2H23 and on as generative AI and machine-learning workloads grow
Artificial intelligence (AI) continues to dominate headlines with the emergence of generative AI. While we are still in the early stages of this technological transformation, generative AI has captured the imagination of many. Semiconductor companies, particularly those powering AI servers, remain the greatest beneficiaries of this trend.
Despite the positive outlook, challenges stemming from an uncertain economic environment, seasonality, and a brief absorption phase led hyperscale cloud service providers to curb capital expenditure (CapEx) spending in 1H23. Overall, cloud service providers showed sluggish CapEx growth in the negative mid-teens HoH. However, Google saw a moderate increase, and Microsoft experienced a significant uptick in capital expenditure due to a refresh cycle and an expansion of computing capacity to support market demand and growth objectives.
For 2H23, our algorithms project positive mid-single-digit growth, signifying a substantial acceleration in data center capital expenditure compared to the first half. Although we still anticipate ending the year with a mid-single digit decrease in spending compared to 2022. Notably, the recent shift in capital expenditure from conventional servers to AI servers bodes well for Nvidia's data center solutions.
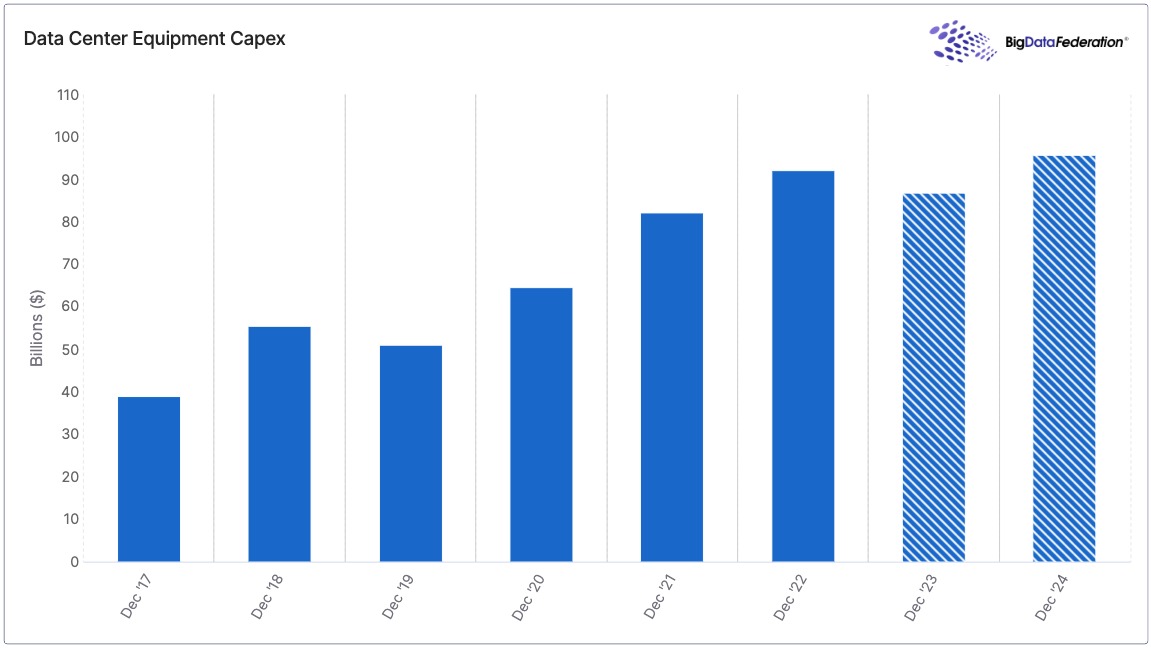
Looking ahead to 2024, our machines forecast high-single-digit growth year-over-year. Supporting the positive turnaround are the sustained adoption and expansion of AI and machine learning workloads, even amidst economic uncertainty. Additionally, we still foresee a continued and steady migration of enterprise workloads to the cloud. Our models indicate that the trend will likely persist into 2025 and onward.
Our algorithms estimate that sixty percent of CapEx spending will originate from three major hyperscale cloud service providers: Amazon, Microsoft, and Alphabet. Another twenty-five percent will come from Meta, Apple, and Chinese hyperscale cloud providers like Alibaba, Baidu, and Tencent. While the rest will be from smaller players, such as IBM, Oracle, SAP, eBay, Salesforce, PayPal, and ServiceNow. Amongst these, Oracle experienced the largest positive growth and is emerging as a major player in the hyperscale cloud service provider landscape.
Overall, economic factors remain at the forefront in 2023. The Fed may have reached the ceiling with aggressive rate hikes, and the combination of hopes for a soft landing along with AI opportunities has fostered cautious optimism for a resurgence in capital spending in the coming years.
Published by Big Data Federation · All insights · Subscribe to Insights