Big Data, Artificial Intelligence, and Machine Learning Will Drive Data Center Growth
By Big Data Federation, Inc.
-
Heavier workloads for AI applications remain the key driver of computing and data storage demands
-
Two-thirds of spending will come from three major hyperscale cloud service providers (Amazon, Microsoft, and Alphabet)
-
Our machinery predicts capital expenditures will flatten into next year for a brief absorption phase
Data centers emerged victorious from the consequences of the pandemic as it catalyzed technological adoption and will maintain their winning streak to meet climbing demand. We project that 2022 will be another solid year, albeit at a deaccelerating growth rate. Hyperscale cloud providers1 will continue expanding capital expenditures (CapEx) by increasing capacity at existing facilities as well as building new data centers in the U.S. and overseas.
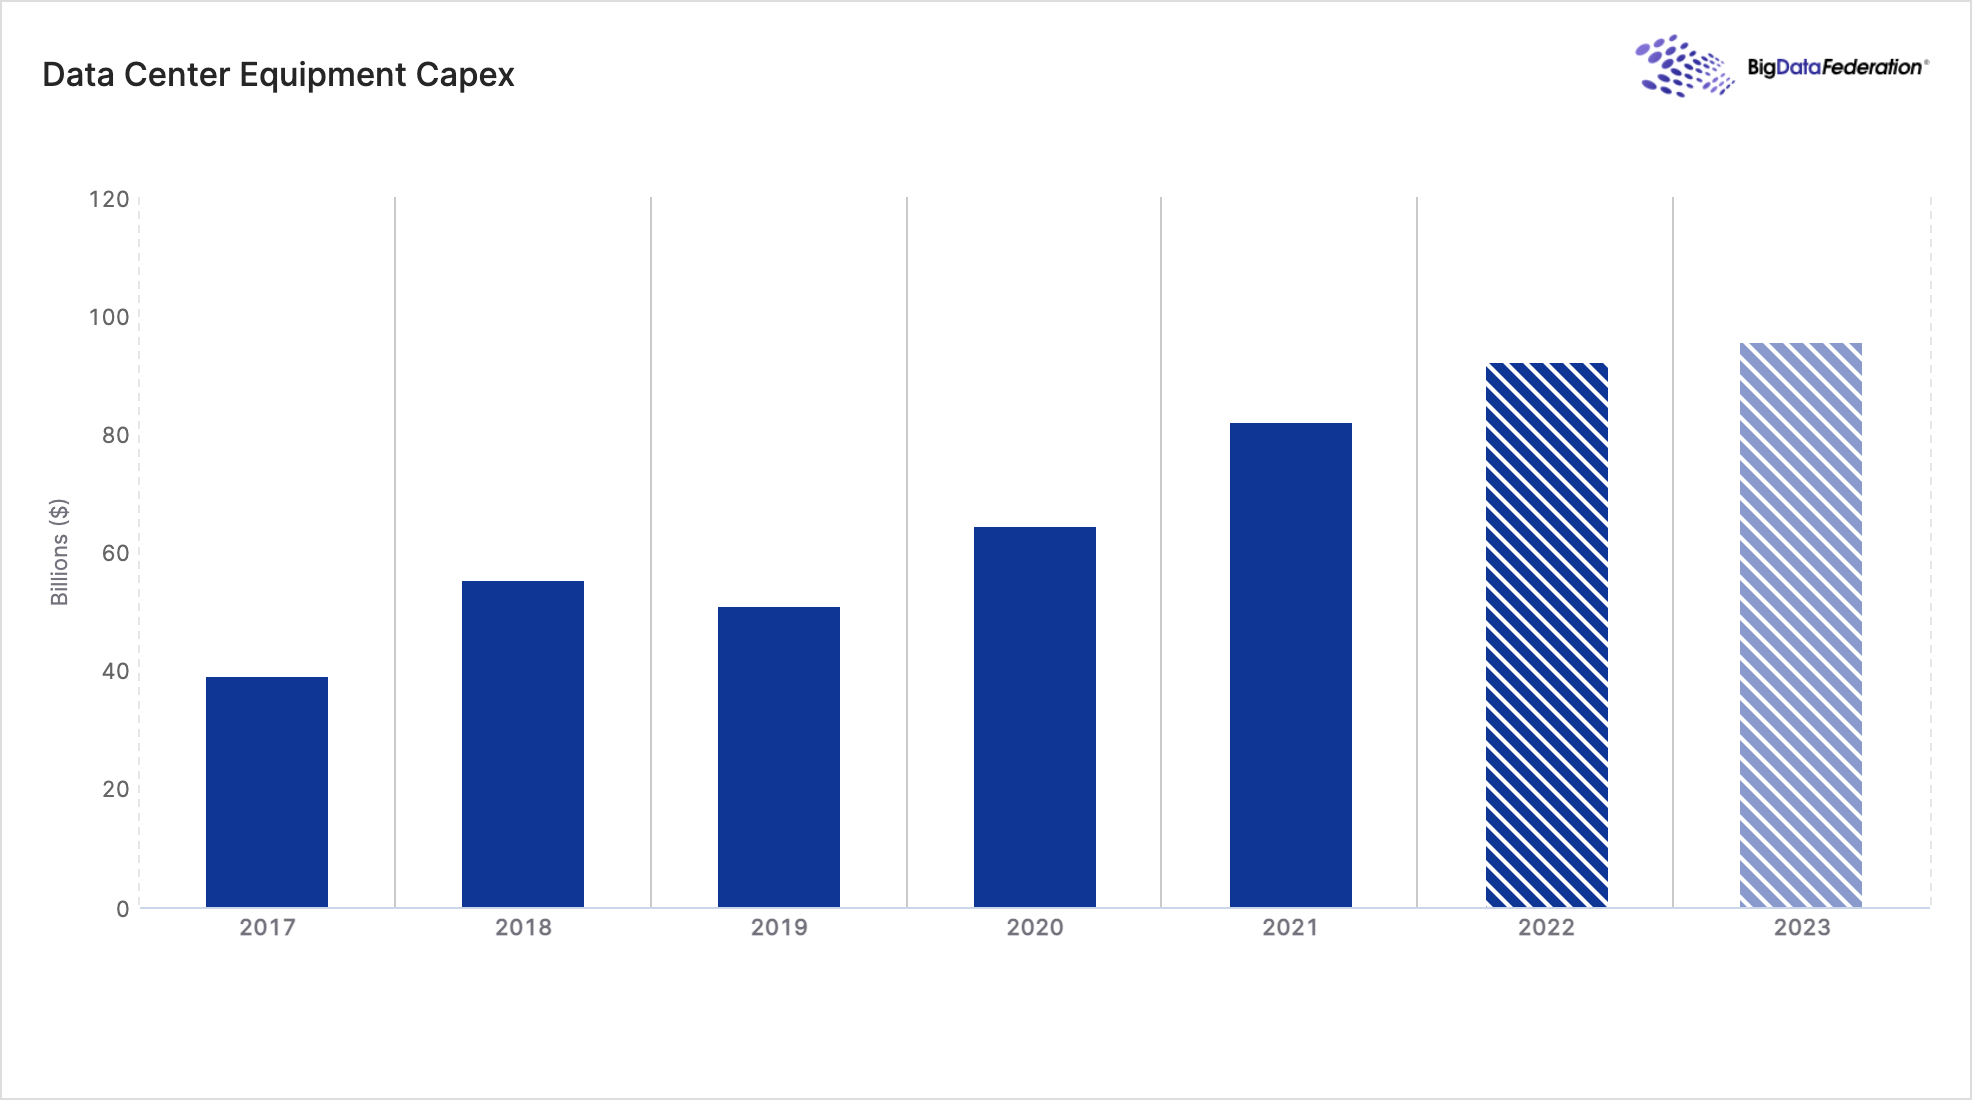
In 2022, our algorithms forecast data center equipment (compute, network, and storage) spending to grow in the mid-teens year-over-year (YoY). While YoY growth is approximately 20% during 1H22, it will cool to a mid-single-digit figure in 2H22. Two-thirds will come from three major hyperscale cloud service providers (Amazon, Microsoft, and Alphabet), one-quarter will be from Facebook, Apple, and China’s Alibaba, Baidu, and Tencent – while the rest will be from smaller players.
Most enterprise workloads continue to migrate to the cloud, especially as multi-cloud tenancy gains momentum. Moreover, massive amounts of data are being collected daily as Internet of Things (IoT) devices are progressively integrated into our everyday lives. Near-ubiquitous wireless networks (4G/5G) and high bandwidth wireline can transport data at low latencies and more economical rates.
Naturally, this generates big data that are available for analytics. Larger datasets translate into heavier workloads for AI/ML training leading to higher computing requirements in data centers. These trends are evident in the number of U.S. data processing employees, tripling its growth rate since 2019.
2023 will face pronounced headwinds due to higher interest rates, inflationary pressures, and recession fears. Therefore, our machines predict capital expenditure to be flat, registering mid-single-digit growth as data centers go through a brief absorption phase2 – after three years of solid CapEx growth. Although, the sustained adoption of cloud usage by enterprises, the expansion of AI/ML workloads, and future investments in edge computing will return strong growth to data center CapEx in 2024.
1 AAPL, AMZN, BABA, BIDU, CRM, EBAY, GOOGL, IBM, META, MSFT, NOW, ORCL, PYPL, SAP, and 700-HK
2 Period when utilization across data center equipment continues to increase until it reaches the expected max threshold before requiring additional capacity
Published by Big Data Federation · All insights · Subscribe to Insights