An Outperforming Value Momentum Strategy
By Big Data Federation, Inc.
Value and momentum factors are among the foundational cornerstones of quantitative equity investing. A value-plus-momentum strategy for S&P 500 stocks seeks to capture two well-documented equity return premia while maintaining broad market characteristics.
In this piece, we present a value-plus-momentum strategy which begins with the full S&P 500 universe and applies a value filter based on Price-to-Book (P/B) ratio, selecting stocks at the start of each quarter with relatively lower valuations compared to peers. This first step emphasizes companies whose market prices remain modest relative to their accounting equity, a classic indicator of value that has been shown over long horizons to identify firms with favorable risk-adjusted return potential.
From this value-screened subset, a six-month momentum filter is applied to identify stocks exhibiting positive and persistent price trends, helping avoid so-called “value traps” and improving timing. The resulting portfolio is market-capitalization weighted and rebalanced quarterly, ensuring that larger, more influential companies maintain proportionate representation while balancing responsiveness to changing fundamentals and momentum signals with transaction cost efficiency.
As demonstrated in the chart below, the value plus momentum strategy has outperformed the S&P 500 Index benchmark. The strategy offers a systematic framework that integrates valuation discipline with trend confirmation. By anchoring the selection process to the S&P 500, the strategy retains sector diversity and liquidity comparable to the benchmark.
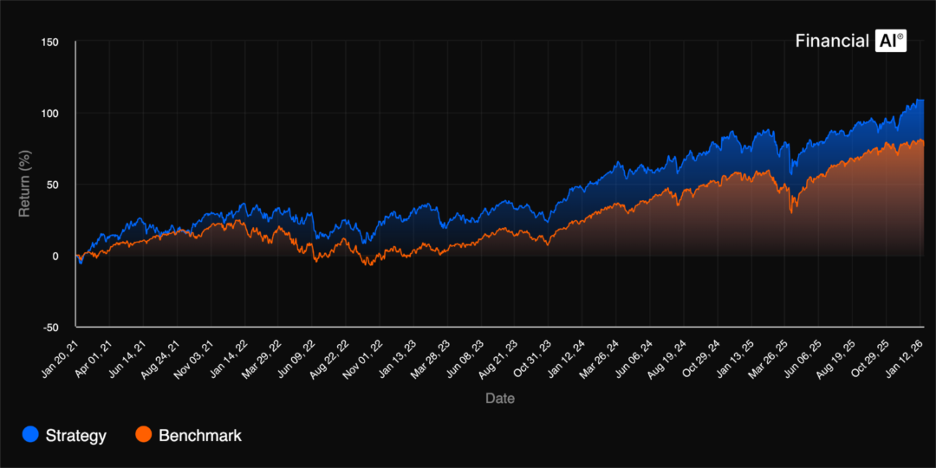
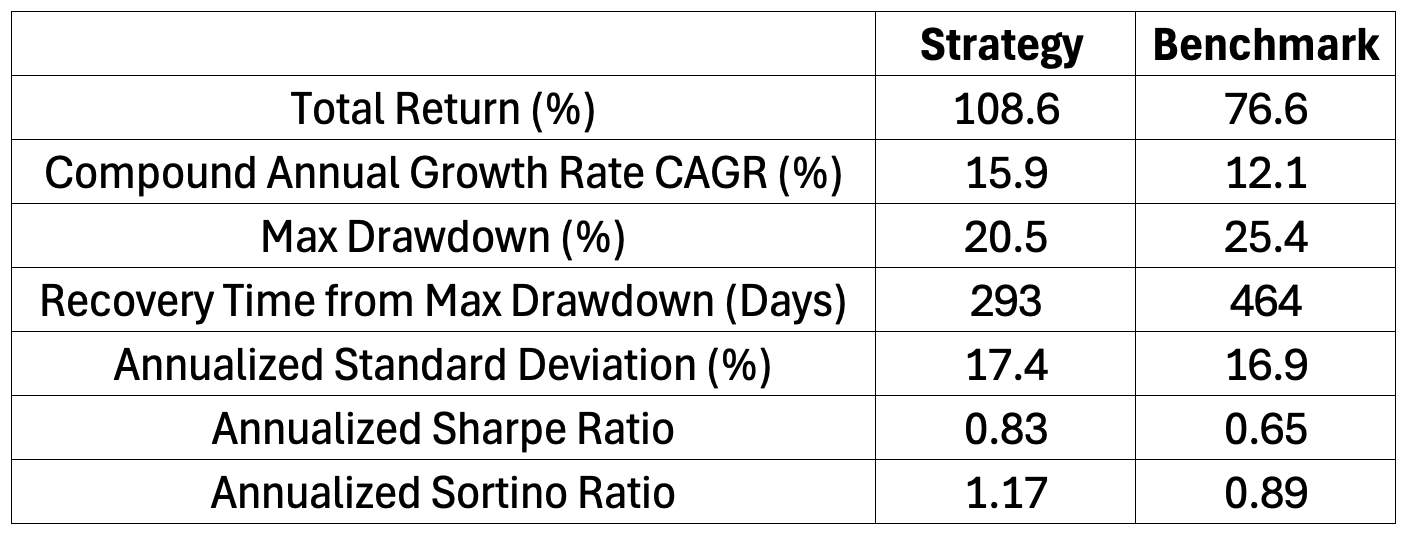
Robust backtesting further validates the strategy, with the table below highlighting its superior risk-return profile. For instance, the strategy’s total return is 108.6%, compared with the benchmark’s 76.6%. More notably, the strategy achieves a 1.17 Sortino ratio versus 0.89 for the benchmark, demonstrating meaningfully better downside risk control while generating superior returns.
 |
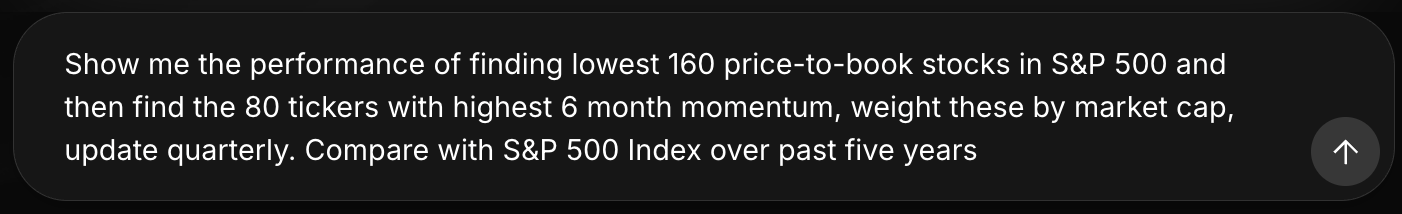
With thefinancial.ai, strategies like a large-cap value plus momentum strategy can be built and backtested end-to-end in minutes on point-in-time data, with no survivorship bias. A simple natural-language prompt like below, is all it takes to generate institutional-grade results that are fully transparent – downloadable and independently verifiable.
 |
Published by Big Data Federation · All insights · Subscribe to Insights