AI-Assisted Hedging Strategies: Part 2
By Big Data Federation, Inc.
Effective hedging strategies are one of the most sought after obejctives in portfolio management for long-term investors. Widely used approaches such as the collar option strategy have proven to be expensive and ineffective during the recent bear market.
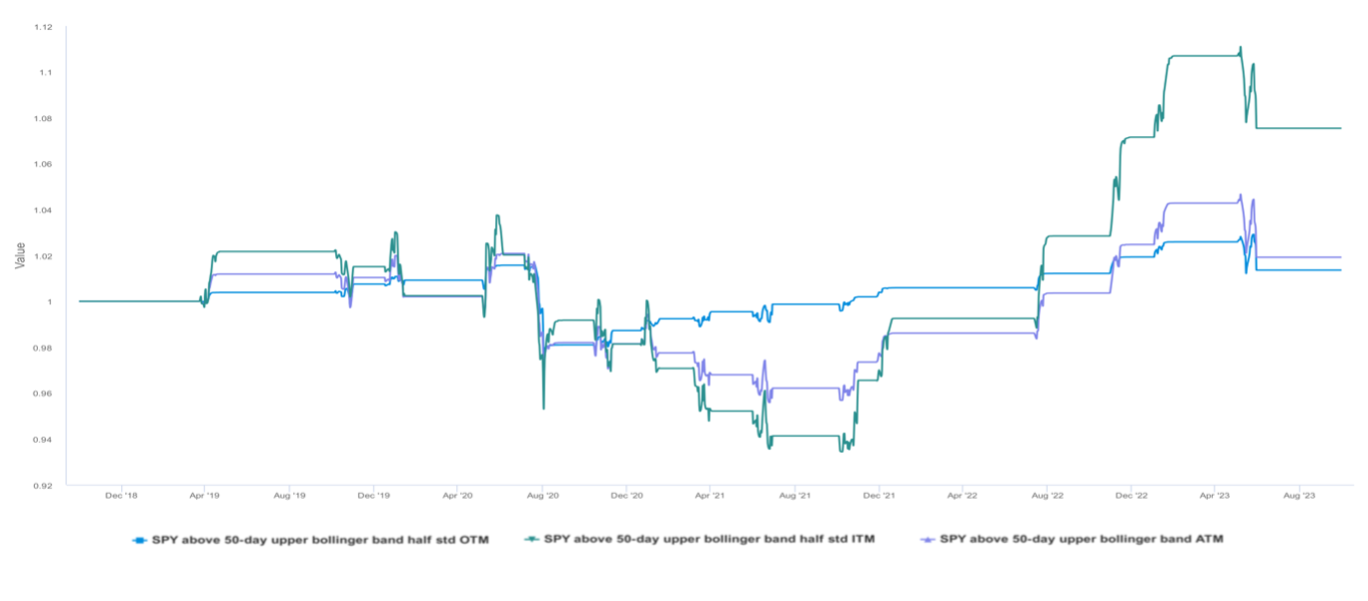
In our hedging mini-series publications, we build and evaluate hedging strategies use our no-code financial AI engine, OdinUltra. In Part 1, we considered a mean-reversion hedging strategies for a typical large-cap core portfolio represented by SPDR S&P 500 ETF Trust (SPY) that sell monthly calls when markets have run up significantly. Specifically, when SPY is above the 2-standard deviations (std) upper 50-day Bollinger Band, we can write:
-
0.5 std out-of-the-money (OTM) monthly calls, or
-
At-the-money (ATM) monthly calls, or
-
0.5 std in-the-money (ITM) monthly calls.
Once we enter into a call contract, we will hold the call till expiration. The backtested NAV curves of these strategies for Oct 2018 – Oct 2023 are as follows.
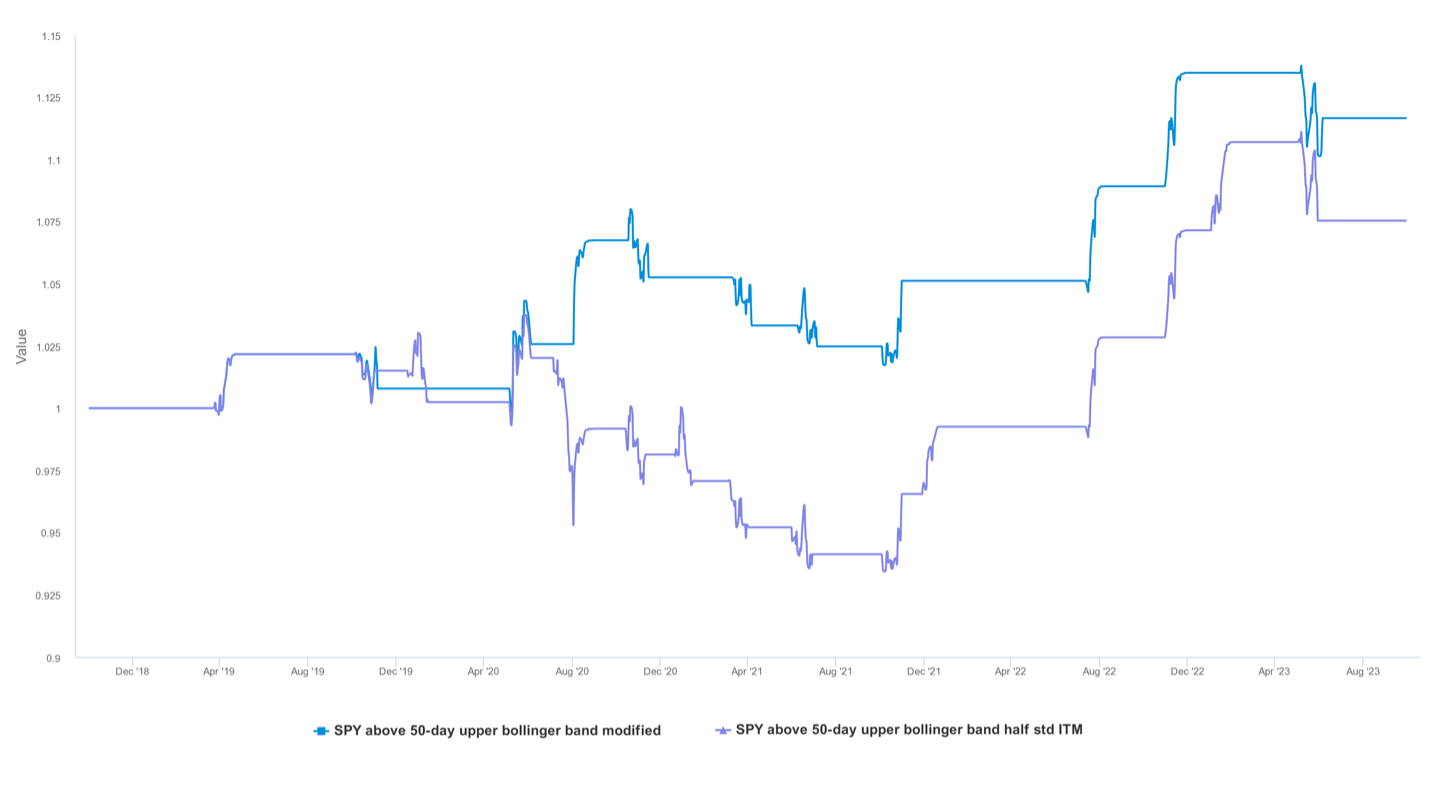
 Note that the trade entry is based on mean reversion of SPY using an 50 day Bollinger band, we can add a further condition by requiring additionally that the Chande momentum index be above the 90% percentile over one year. Other alternative technical indicators can be tested similarly. The NAV curves of the modified strategy versus the third in-the-money option are as follows.
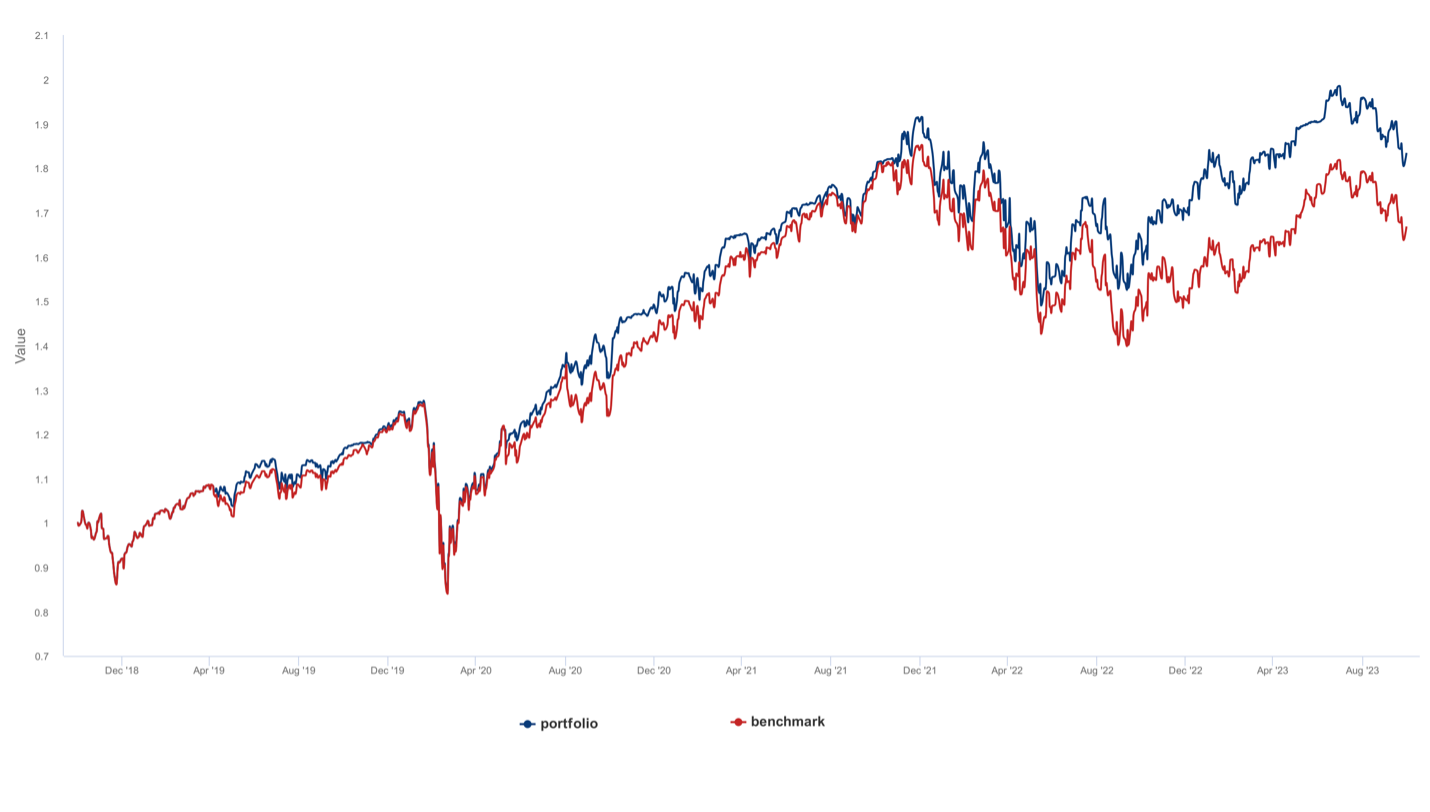
 In the following chart, we show the NAV curves of a total return of SPDR S&P 500 ETF Trust SPY (maroon) versus the total return for the ETF SPY hedged with the modified 0.5 std ITM monthly call writing. The notional amount of these calls is assumed to be 100% of AuM. Note that when the hedging strategy is triggered, we have a covered call striked at 0.5-stdev in-the-money and about 1 month to expiration. The hedged portfolio outperforms the unhedged SPY benchmark in both total return and risk return measures such as Sharpe ratios in the above backtesting period.
Backtesting these strategies requires our calculation engine to accurately identify the correct options. Data cleansing, modeling, and validation are essential parts of the process. For a typical quantitative researcher generating the above results can take anywhere from a few days to several weeks, depending on data availability and technology infrastructure. With OdinUltra, these tasks can be accomplished in just a few minutes. Users can also download position and NAV details for further study from OdinUltra if so desired.
In conclusion, systematic and disciplined hedging strategies can be build on OdinUltra using complex logics to improve risk return characteristics. Users can quickly generate detailed backtest results and may further improve on these results with multiple hedging strategies using OdinUltra, which empowers asset managers to leverage their domain expertise throughout the entire investment process to explore, construct, verify, and deploy investment ideas and theses quickly.
To learn more details on these strategies or construct your own hedging strategies, you may request a trial at OdinUltra.ai.
About OdinUltra
OdinUltra is a cutting-edge no-code specialized AI platform, designed to cater to a wide array of professionals in the asset management industry. It is a battle-tested specialized partner that empowers users including discretionary, quantitative, multi-asset, and multi-strategy managers to harness the immense potential of big data and sophisticated investment techniques. From idea exploration and construction to verification and deployment, OdinUltra is an all-encompassing tool. Asset managers can enhance existing products and rapidly develop new ones, securing a competitive edge in the dynamic world of asset management.
Published by Big Data Federation · All insights · Subscribe to Insights